Options Open

If you’re already getting our Policy Updates, you may have heard enough from us this week. For the two-thirds of you not already subscribed, this is where we share occasional updates on — yes, you guessed it — policy.

It may not surprise you that the vast majority of the many messages I’ve received have been about the narrow conditions for qualifying for Founders’ Relief. We’ll be pushing for it to be widened, but there’s also a lot more to the Budget than this.

First, as our Adviser Oliver Claridge set out today in a Policy Update, there is an upgrade to the UK’s two main tax-advantaged share option schemes, Enterprise Management Incentives (EMI) and Company Share Option Plans (CSOP) — the latter rebranded EMI2, which is what everyone will be calling it from now on. At present a CSOP grant eats into what you can then give the same employee under EMI, because both count towards one £250,000 ceiling. From 6 April 2027 the two are counted separately, the CSOP limit doubles from £60,000 to £120,000 a head, and options can run for 15 years instead of 10. This is a big deal.

Callum Hemsley, CEO of TypeDB, is “cautiously optimistic”. He messaged to say: “There is plenty to like as an entrepreneur in this Budget, particularly the £80 million for sovereign AI procurement, greater use of challenge-based procurement, and a clearer definition of UK suppliers.” And as I covered in my Forbes article, entrepreneurs had positive things to say about the British Business Bank doubling its commitment to women-led businesses and funds to £200 million, alongside a new scale-up programme for female founders, and a higher trading allowance for sole traders.

One change we were particularly happy to see answered our long-standing call — most recently in Job Creators 2026 — to expand the list of universities whose alumni would qualify for the High Potential Individual visa. In fact, just the day before the Budget I was reiterating this when giving evidence to the Business, Innovation, Science and Trade Committee.

Finally, as our Patron Steve Rigby wrote on LinkedIn:

“The roadmap to retaining 100% of business rates locally by 2030, with 20% flowing to mayors from next year, and a share of income tax from 2028, is the most consequential policy initiative announced today. It is the first serious attempt in a generation to link regional growth with regional revenue. For companies headquartered outside London, it means local leaders having real money and a direct stake in businesses’ success. It also means we need to be at the table as mayors decide how to use these funds.”

As we have argued before, devolution comes in two forms. The first transfers funds, on the assumption that decisions made closer to the ground will be better ones. The second lets places keep the proceeds of growth, and bear the cost when it doesn’t come. It is only this latter model that alters the incentives at play. This is the right sort of devolution.

National Importance

I would hate to fall into the rightly parodied class of organisations calling the Budget a “missed opportunity”, but it didn’t address the key concern of entrepreneurs in our network. As I wrote in our snap reaction:

“Our latest Entrepreneurs Survey with Blick Rothenberg, which closed just before the Budget, found that cutting Employer National Insurance was founders’ top Budget ask. Reducing the obligations on employers in the Employment Rights Act was entrepreneurs’ fourth-highest priority.

“With the National Living Wage rising 3.9% to £13.21, nearly a million young people not in education, employment or training, and unfair dismissal rights after six months and uncapped compensation from January, the number one issue facing entrepreneurs and the next generation remains unaddressed.”

As Bugrahan Eroglu, Founder at SpeakLab, wrote to me:

“At 22, I built SpeakLab on my own — an AI-powered language-learning platform now used by more than 25,000 learners. My next challenge is building a team to improve the product, reach more learners globally, and expand partnerships with universities and language schools. I welcome the Budget’s expansion of employee share options, but reducing employer National Insurance for a startup’s first few hires would make a more immediate difference at this stage.”

The forthcoming Milburn Review will hopefully address some of this. But the cost of employment and the dearth of opportunities for the next generation to work are such monumental problems that they need more than a pilot of a Young Entrepreneurs Allowance (welcome as it is, and reflecting our Starting Out and Starting Up report).

Thanks for reading Perennial Gale!

Depledge of Allegiance

Regular readers will already be aware of the high regard in which we hold Alex Depledge, the outgoing Entrepreneurship Adviser to the Chancellor of the Exchequer. In short, everything good that the Government has done for entrepreneurs over the last few years has her fingerprints on it. I’ll share some of her words on LinkedIn in the hope that others with her talent who are reading this follow in her footsteps:

“I took this job because I want Britain to build companies that compete with the biggest on the planet. I want the next Magnificent Seven to include British businesses. I want companies like Revolut to scale and stay here, and for people across this country to benefit from their success. That has been the objective all along.

“Having built two businesses myself, I know how much founders put on the line. I also know what can happen when an ambitious company gets the backing it needs. The jobs that creates, the opportunities it gives to people, the investment and tax revenues it generates as it grows.

“This is why I believe so deeply in entrepreneurship as an engine of growth. Britain’s prosperity urgently depends on our ability to turn our extraordinary ideas into extraordinary companies. Our future rests on it.”

Thank you for your service.

Changes to Tax Advantaged Employee Share Schemes

We have published our snap reaction to the Autumn Budget, as well as a deeper dive. In this piece, tax expert Oliver Claridge looks more closely at the specific changes to tax-advantaged employee share schemes.

The Budget 2026 announced that the following changes will take effect for options granted on or after 6 April 2027.

What are CSOPs (now rebranded as EMI2)?

The share scheme formerly known as Company Share Option Plan (CSOP), now to be rebranded as EMI2 (although still referred to in legislation as CSOP), allows (listed or independent) companies of any size to grant tax advantaged share options of up to £60,000 to each or certain employees (there is no requirement to offer to all employees but each employee has their own independent limit). There are no income tax or national insurance charges on qualifying options on grant (assuming exercise price is equal to at least market value as at the date of grant) or their exercise as long as the employee exercises the option within ten years, and:

  • at least three years have elapsed since the date of grant, or

  • within six months of cessation of employment as a “good leaver”, or

  • within 12 months of death (by their personal representatives), or

  • within six months of certain cash takeovers.

What are EMI Schemes?

EMI allows companies which meet certain very specific criteria to grant up to £250,000 options to employees.

Broadly, to qualify a company must have less than £120m of gross assets, carry on a qualifying trade (and there are a number of exceptions that are not qualifying trades such as property development and financial activities), have fewer than 500 full-time employees and shares must be over the parent company of a group.

As with CSOP/EMI2, there is typically no tax charge on either grant or exercise of the qualifying option.

What is changing from 6 April 2027

  • The total value of CSOP/EMI2 options is being increased to £120,000 and the ten-year exercise period is extended to 15 years for options granted after April 2027.

  • Previously, there was in effect an “aggregate” cap on EMI and CSOP/EMI2 grants of £250,000 as EMI had a hard cap of £250,000 and CSOP/EMI2 grants counted towards this figure. The Government will now scrap this interaction, so EMI and CSOP/EMI2 limits can operate independently.

  • The EMI exercise window following disqualifying events will also be extended to 180 days to give EMI holders more time to take steps to protect their tax advantaged status.

  • EMI status was previously not lost if the company stopped being independent because it was sold to an employee ownership trust (EOT); the rules now extend to companies arranging to become controlled by an EOT.

Employers will now have more scope to reward and attract highly productive employees in a tax advantaged way and can now take full advantage of both EMI and CSOP/EMI2 schemes. This should provide start-ups and scale ups tax efficient ways to draw in needed talent as they build the next generation of British business.

What the government is intending is that companies first use EMI, then to the extent that they are too large or carry on businesses that don’t qualify they then use CSOP/EMI2. A potential upside is that shares acquired on an exercise of EMI options may benefit from business asset disposal relief (BADR) without needing to satisfy the normal BADR conditions.

Oliver Claridge is a Senior Associate at Forsters and an Adviser to The Entrepreneurs Network.

Forsters has an Autumn Budget 2026 hub, containing analysis and insights. If you would like to learn more, you can find it here. This Policy Update is intended for informational purposes only and does not constitute legal advice. For the most accurate and up-to-date information, please contact Forsters for more.

A Deeper Dive into the Budget

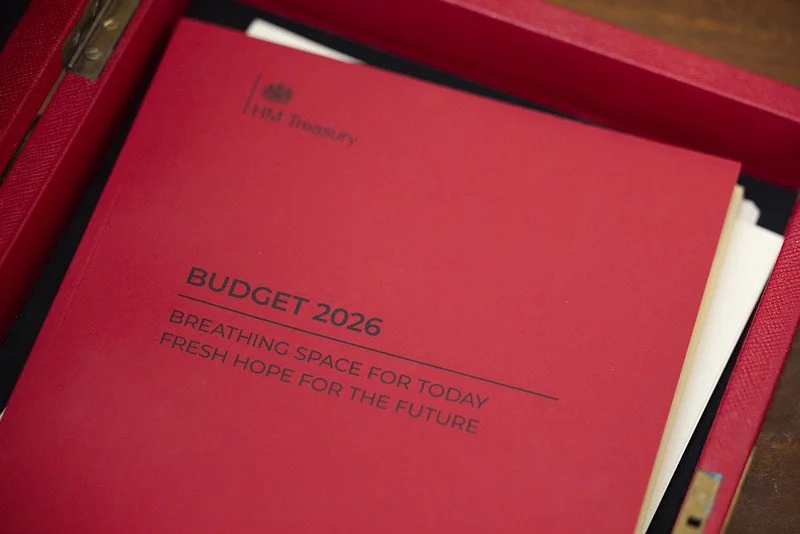
Our team gave snap reactions to the 2026 Budget yesterday. Below, we look in more detail at what it means for entrepreneurs. Alongside the Red Book, the Government published an Entrepreneurship in the UK Prospectus, which sets out many of the measures covered below.

(Source: HM Treasury)

Tax for founders and investors

Founders’ Relief and BADR

From April 2027, founders and significant early investors who sell shares in a high-growth, innovative company will pay Capital Gains Tax at 10%, instead of the usual 24%, on up to £10 million of lifetime gains. The qualifying conditions for “high-growth”, however, are narrow.

Founders need to have:

  • owned at least 25% of the company when it started trading;

  • held their shares for at least five years before selling; and

  • been a UK tax resident for five years before the sale.

The company needs to:

  • be a UK trading company still in its original line of business;

  • have had at least £10 million turnover and 15 full-time staff in the year before the sale; and

  • pass two of three tests:

    • Turnover test: turnover growing by an average of 25% a year for three years in a row, from at least £10 million, reaching roughly £20 million.

    • Headcount test: full-time staff growing by an average of 25% a year for three years in a row, from at least 15. Directors and contractors don’t count.

    • Innovation test: at least £1.5 million of R&D spending claimed under R&D tax relief in the three years before the sale.

The Government is consulting on the detailed design until 30 November 2026, and founders can respond to the technical consultation.

The lifetime limit on gains eligible for Business Asset Disposal Relief (BADR), the 18% rate of CGT on qualifying disposals, has been halved from £1 million to £500,000. According to the Government, three-quarters of BADR claimants will still receive relief on their entire gain after this change.

Many of these measures respond to the Government’s Tax Support for Entrepreneurs call for evidence. Technical details of each tax change are in the Budget 2026 tax-related documents.

Changes to EMI

Last year’s Budget expanded Enterprise Management Incentives (EMI) to companies with up to £120 million in gross assets and 500 employees. This year, the Government has turned to the Company Share Option Plan (CSOP), used by larger companies that have outgrown EMI.

From 6 April 2027:

  • the individual CSOP limit will double from £60,000 to £120,000;

  • the £250,000 combined limit across EMI and CSOP will be removed, so employees can hold up to £370,000 in tax-advantaged options across both schemes;

  • the CSOP exercise period will be extended from 10 to 15 years; and

  • CSOP will be renamed EMI2, to make clear that it is intended as the next step after EMI.

EMI itself will also become more flexible. Employees will have 180 days, up from 90, to exercise their options after a disqualifying event. Companies moving to an Employee Ownership Trust will keep access to EMI. Companies will no longer need to notify HMRC separately when they grant EMI options, and will report grants in their end-of-year return instead.

The Budget did not say whether CSOP’s other rules will change. Under the current rules, employees generally need to wait three years after their options are granted to receive the tax relief, unless an exception applies, such as leaving the company for certain reasons. EMI has no such waiting period.

SEIS, EIS and VCTs

The Government will simplify the Seed Enterprise Investment Scheme (SEIS), the Enterprise Investment Scheme (EIS) and Venture Capital Trusts (VCTs). HMRC will also work with industry to improve Advance Assurance, the process founders use to confirm that their company qualifies before raising money.

The Government will also take action on excessive fees charged to investors, so that more tax-advantaged investment reaches the companies it is meant to support. This includes strengthening HMRC guidance and compliance activity, and working with the Financial Conduct Authority to improve transparency on fees.

R&D tax credits

The Claim Notification Form will be scrapped from 1 April 2027 and the Additional Information Form will be simplified from autumn 2027.

Trading Allowance

From 6 April 2027, the Trading Allowance will triple from £1,000 to £3,000, so individuals can earn up to £3,000 a year from trading, such as a side business, and miscellaneous income without paying tax on it.

Cost of employment

On 1 April 2027, the National Living Wage will rise by 3.9% to £13.21 an hour, and the rate for 18- to 20-year-olds will rise by 3.9% to £11.27. The Budget did not change the headline rates of National Insurance contributions.

Talent and visas

High Potential Individual visa

The High Potential Individual visa allows graduates of leading overseas universities to work in the UK for two years, or three with a PhD, without a job offer or sponsor. Eligibility will expand from graduates of the world’s top 100 universities to the top 150, with a proportional increase to the current cap of 8,000 applications a year.

Graduate visa

From January 2027, the Graduate visa for international students graduating from UK universities is due to fall from two years to 18 months. However, graduates of high-compliance universities with strong labour market outcomes will keep two years. PhD graduates will continue to receive three years. The Government has not yet published which universities will qualify.

Legislation on non-competes

The Government confirmed plans to legislate to restrict non-compete clauses, applying the restrictions across the whole economy. It will also consult shortly on the wider use of restrictive practices, before setting out its full position in early 2027 ahead of legislating. For background, see the Government’s working paper on options for reform.

Visa salary requirements

From spring 2027, minimum salary thresholds for each occupation will fall from the median to the 25th percentile of wages, with thresholds updated each year in line with wage growth. The separate discounts for those studying, recently graduated or in professional training will be combined into a single figure and the PhD discount removed. The most highly skilled workers will also get up to six months to find a new job if they lose their current one, the exact period depending on the duration of their previous employment.

Access to finance

British Business Bank

The British Business Bank’s financial capacity will increase by £5 billion to £30.6 billion, including £1.4 billion to invest in equity funds backing high-growth businesses, £450 million for a new venture debt product, which lets innovative firms borrow without giving up more equity, and further support for Community Development Finance Institutions, which target SMEs.

Capital markets

The Government says it will keep a cut to Stamp Taxes on Shares “under review”, recognising the potential economic benefits of a cut.

Widening access

Female entrepreneurship

Working with the Women in Tech Taskforce, the Government unveiled a fresh package to support women in technology and tackle barriers facing female founders and workers. The package includes two new voluntary standards on workplace culture and on investment practices, and a new scale-up women’s programme to support women starting and growing tech companies.

Young Entrepreneurs Allowance

The Government will pilot a Young Entrepreneurs Allowance in England, helping successful applicants with their living costs during the first year of their business. Details have not yet been published.

Scale UK

Scale UK will be a single access point to government support for high-growth businesses, bringing together existing support, including Innovate UK’s Velocity scheme, the Regulatory Innovation Office and the British Business Bank. A new Scale UK Connect pilot will give 200 high-growth firms expert advice, investor connections and international opportunities.

AI and Tech

Sovereign AI

The Government will provide an extra £140 million for Sovereign AI, including £60 million for the Sovereign AI Fund from 2027–28 to invest in promising British AI firms, with a new focus on physical and industrial AI, and £80 million for its R&D procurement scheme, so British AI companies can work on government challenges in health, AI security and defence.

Data Centre Covenant

The new Covenant offers strategic data centres faster grid connections in return for meeting conditions on energy, local investment, environmental standards and security. The Government is also backing Ofgem in clearing speculative applications to the grid and allowing developers to build their own grid connections, as set out in the Government’s response to its consultation on accelerating grid connections for strategic demand. However, permission to generate power on site while waiting for a grid connection is limited to “exceptionally strategic” projects.

You can find the detailed policy paper here.

Regulation

Better Regulation Executive

The Government is establishing a new Better Regulation Executive, leading the work on a more streamlined and proportionate regulatory system.

The Government aims to cut the administrative burden of regulation on businesses by 25% by the end of this Parliament, saving £5.6 billion a year. It says it has delivered or identified £2 billion of net savings so far. This Budget identifies a further £413 million to £643 million a year of savings for businesses. Details are in the supplementary document on the 25% target.

For growing companies, the most relevant proposal is to extend the audit exemption that small companies already have to medium-sized companies. At the moment, a company is medium-sized if it meets two of three tests: turnover of up to £54 million, a balance sheet of up to £27 million, and up to 250 employees. If the proposal goes ahead, many of these companies would no longer need a statutory audit, and subsidiaries would also find it easier to qualify for an exemption. The proposals are part of the Modernising Corporate Reporting consultation, which closes on 30 November 2026.

Regulating for Growth Bill

As previously announced, the Regulating for Growth Bill will give the Government new powers to temporarily adapt existing rules so that new technologies can be tested. Proposed early uses include testing new medicines and medical devices with the MHRA, developing drones and autonomous systems, and AI Growth Labs for AI products and services.

Also in the Budget

  • From October 2027, online marketplaces will collect VAT on sales by UK VAT-registered sellers, and by other UK businesses selling at least £90,000 a year on a platform. Personal sales, second-hand goods and business-to-business sales are excluded (you can read the consultation outcome here).

  • From April 2029, self-employed fathers, partners and adopters will be eligible for parental pay.

  • From April 2029, self-assessment taxpayers who make payments on account will make more regular payments during the year. Businesses will also need to set up a direct debit for amounts still owed on VAT and PAYE returns.

  • Taxpayers joining Making Tax Digital for income tax in April 2027 will not receive penalty points for late submission of their first four quarterly updates.

Philip will be back with further analysis in tomorrow’s Perennial Gale. Make sure you are subscribed to all of our newsletters to keep on top of further developments and stay in touch to join future events.

Autumn Budget 2026

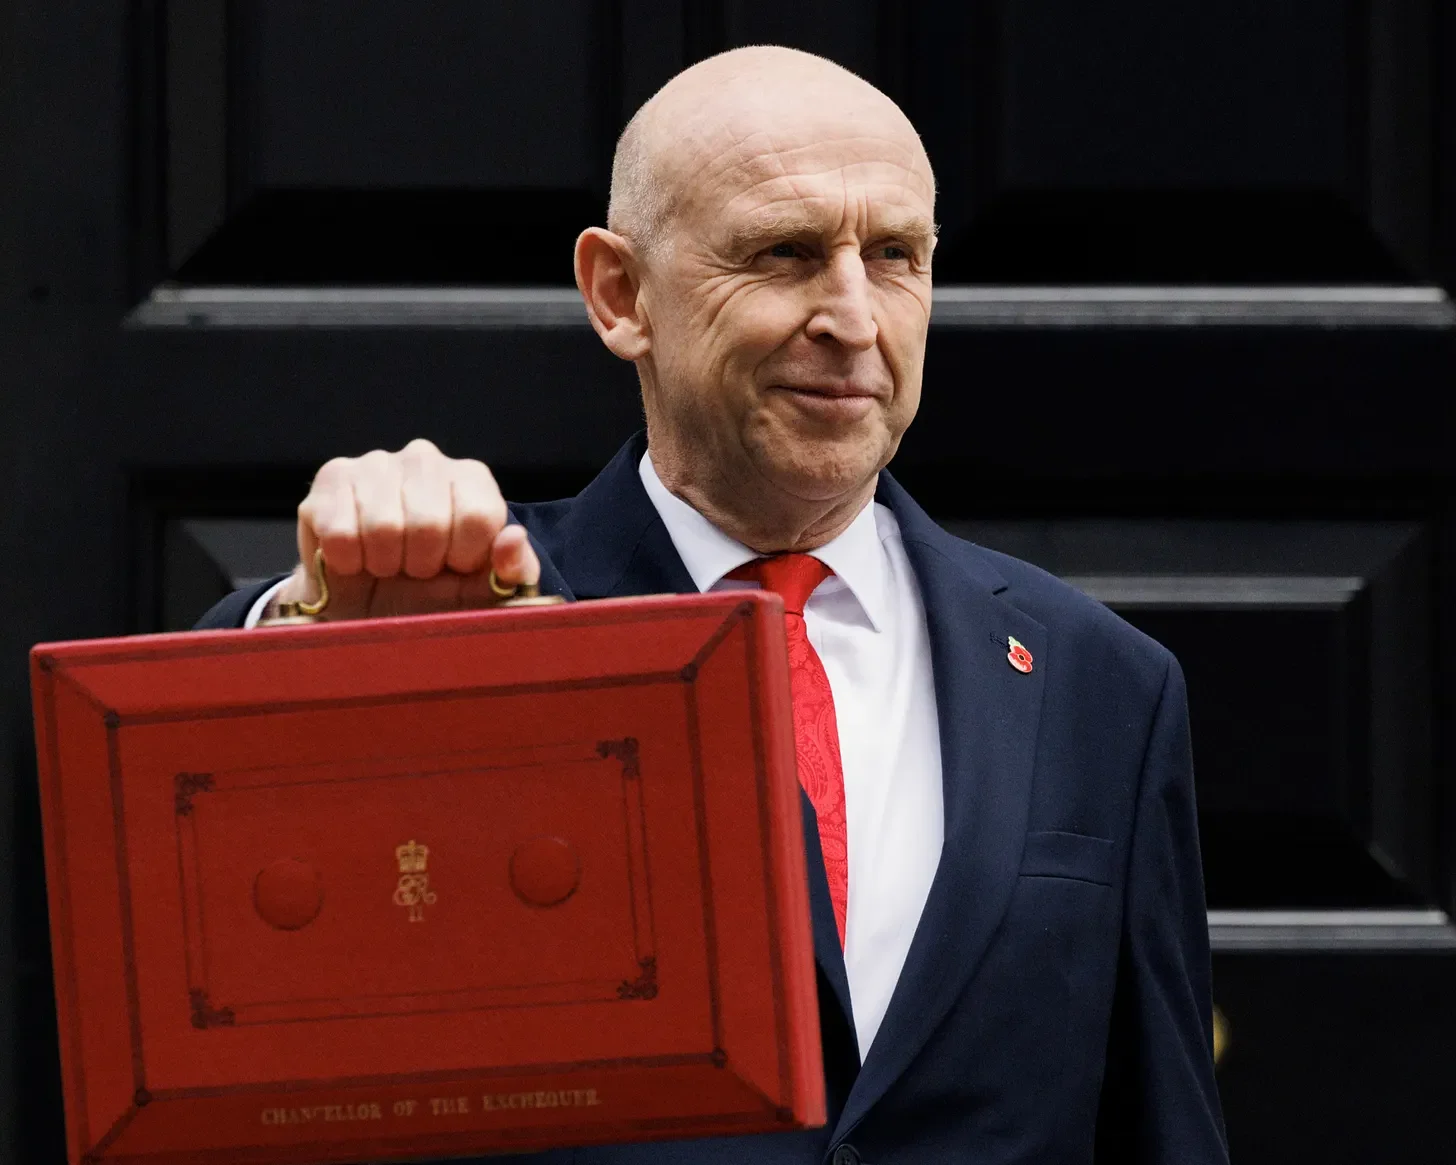
This afternoon, Chancellor of the Exchequer John Healey delivered the 2026 Autumn Budget. Read below for our team’s snap reaction to some of the main points concerning economic growth, innovation and entrepreneurship.

We’ll be digging into things in more depth later in the week — so stay tuned by subscribing to our Friday newsletter, Perennial Gale, if you haven’t already.

On the Autumn Budget in general

Philip Salter, Founder of The Entrepreneurs Network said:

“Founders went into this Budget expecting the worst. Our Entrepreneurs Survey found that 61% expected it to be bad for entrepreneurs, and just 7% expected it to be good.

“There were certainly things to welcome. Those with side hustles and people new to entrepreneurship will be encouraged by the tripling of the Trading Allowance to £3,000, while EMI2 will help scale-ups compete for top talent. The expansion of the High Potential Individual visa to graduates of the top 150 institutions and keeping the Graduate visa at two years for graduates of high-compliance universities are also crucial to attracting and retaining talent.

“But the Budget ducks the cost and risk of employing people, founders’ current number one issue. And while Founders’ Relief might sound like a return to Entrepreneurs’ Relief, as proposed, it looks set to be very narrow.”

On Founders’ Relief and BADR

Philip Salter, Founder of The Entrepreneurs Network, said:

“The casual observer could be forgiven for thinking that a 10% rate of Capital Gains Tax on up to £10 million of lifetime gains marks the return of Entrepreneurs’ Relief, which was cut back in 2020.

“However, the technical consultation points towards a very narrow definition. Founders would need to have owned at least a quarter of the company from the start, while their companies would need at least £10 million turnover and 15 full-time staff, and to pass two of three tests on turnover growth, headcount growth and R&D.

“At the same time, the lifetime limit on Business Asset Disposal Relief is being halved from £1 million to £500,000. In practice, this means the maximum saving falls from £60,000 to £30,000.”

On the cost of employment

Philip Salter, Founder of The Entrepreneurs Network, said:

“Our latest Entrepreneurs Survey with Blick Rothenberg, which closed just before the Budget, found that cutting Employer National Insurance was founders’ top Budget ask. Reducing the obligations on employers in the Employment Rights Act was entrepreneurs’ fourth-highest priority.

“With the National Living Wage rising 3.9% to £13.21, nearly a million young people not in education, employment or training, and unfair dismissal rights after six months and uncapped compensation from January, the number one issue facing entrepreneurs and the next generation remains unaddressed.”

On changes to EMI

Mann Virdee, Head of Science and Technology at The Entrepreneurs Network, said:

“Share options are one of the most important ways startups attract talent from larger companies when they can’t compete on salary. Last year’s expansion of Enterprise Management Incentives (EMI) was a welcome start, and today’s announcement builds on that by doubling the individual share option limit under the Company Share Option Plan (CSOP) from £60,000 to £120,000 from April 2027. We welcome the announcement that the combined cap with EMI will be removed, which means that employees will be able to hold up to £370,000 in tax-advantaged options across both schemes.

“However, renaming CSOP as ‘EMI2’ doesn’t make it as generous as EMI. If EMI2 keeps CSOP’s rules, employees will generally need to hold their options for three years to get the tax relief, whereas EMI options can be exercised tax-efficiently at any point, including when a company is sold.

“The Government should also index the limits of both schemes to inflation so their value isn’t eroded again.”

On the expansion of the High Potential Individual visa scheme

Ian Ng, Researcher at The Entrepreneurs Network, said:

“In Job Creators 2026, we found that 54 of the UK’s 100 fastest-growing companies have at least one foreign-born founder. Attracting and keeping high-skilled talent is vital to Britain’s startup ecosystem, so we welcome the expansion of the High Potential Individual visa to graduates of the world’s top 150 institutions.

“However, if eligibility still depends on general university rankings, standalone business schools such as INSEAD and HEC Paris will be excluded. The Government should also admit institutions that place in the top 50 of the FT or QS Global MBA rankings, or in any of the five broad faculty areas of the QS subject rankings.

“Many of Britain’s foreign-born founders first came here to study, so it is right that the Government will keep the Graduate visa at two years for graduates of high-compliance universities. But building a business takes time. Graduates whose business is being assessed by an Innovator Founder endorsing body should get a further 12 months, so they can build the traction they need to qualify.”

On the Better Regulation Executive

Mann Virdee, Head of Science and Technology at The Entrepreneurs Network, said:

“The Government’s decision to re-establish the Better Regulation Executive, with a mandate to cut outdated regulations and admin burdens on businesses, is welcome. In our latest survey with Blick Rothenberg, 70% of founders said they take a negative view of the level of regulation in the UK. Red tape is hardest for startups, which have to meet many of the same compliance costs as large firms with a fraction of the staff.

“However, re-establishing a unit is the easy part. It needs clear targets, published progress against the Government’s goal of cutting admin burdens by a quarter by the end of this Parliament, and the backing to challenge departments that keep adding rules. It should also work closely with the existing Regulatory Innovation Office and the new Regulating for Growth powers.”

On R&D tax credits

Mann Virdee, Head of Science and Technology at The Entrepreneurs Network, said:

“Scrapping the R&D Claim Notification Form and simplifying the Additional Information Form will make it easier for innovative firms to claim. This matters because R&D tax claims fell by over a quarter in the first full year of the new form. But paperwork is only part of the problem. Founders told the APPG for Entrepreneurship of compliance checks dragging on for two years, only to end with their claims largely upheld.

“In Canada, an R&D claim under review is assessed by an adviser with a science or engineering background, who phones the firm before reaching a decision. In the UK, claims are judged by HMRC inspectors, and HMRC’s panel of subject-matter experts doesn’t review individual claims. The Government should move towards the Canadian model, so that founders can explain their work to someone who understands it.”

On the new Data Centre Covenant

Ian Ng, Researcher at The Entrepreneurs Network, said:

“AI startups need compute to build and scale, yet many UK firms still rely on overseas cloud infrastructure. The Government aims for 6GW of AI-capable capacity by 2030, but its own preliminary estimates suggest we could reach as little as 3.3GW, with viable projects stuck in the grid queue.

“We welcome the Data Centre Covenant’s support for clearing speculative projects from the queue, and greater freedom for developers to build their own grid connections. However, the permission to build on-site power has been limited to ‘exceptionally strategic’ projects. It should be opened up more widely.

“To avoid relying on ministerial discretion, when the Government sets out its definition of a strategic data centre, it should use clear, objective criteria and allow any viable project to generate its own power while it waits for the grid.”

Startup Witness

On Tuesday afternoon, I’ll be giving evidence to the Business, Innovation, Science and Trade Committee alongside Professor Mark Hart, Professor Monder Ram and Jordan Dargue. Our evidence will feed into the Committee’s new inquiry on how businesses get started in the UK.

Having already looked at small business strategy and at how firms access scale-up finance, the Committee is now turning to the earliest stage: how people actually go about founding a business, what conditions make entrepreneurship more likely, whether government policies are effective at encouraging it and how the newly reorganised department will fold innovation policy into that effort.

The Committee plans to assess the UK’s entrepreneurial ecosystem as a whole, draw comparisons with other countries and weigh the parts played by education, finance, innovation and policy in getting businesses off the ground.

There are three ways you can help. First, I’ll be drawing on our latest Entrepreneurs Survey. If you fill it in before it closes on Monday, your answers will be part of the evidence. Have your say today.

Second, you can email me your ideas directly. I won’t be able to raise all of them on Tuesday, but they can also feed into our written response to the call for evidence, which brings me to the third way you can help. You could respond to the call for evidence yourself. There are lots of questions, but the most useful thing a founder can send is an account of what actually happened rather than a view. The strongest submissions are built around a comparison: having started a business abroad as well as here, having founded one a decade ago and another recently, or having considered starting another business after exit and decided not to.

It’s not just for founders, though. Those supporting founders will have their own insights based on their areas of expertise. You can respond to the call for evidence here. It closes at 11pm on Thursday 12 November 2026.

Sage Advice

As anyone who attended our event with James Wise back in January 2024 will know, James — now chair of the UK government’s Sovereign AI Unit — argued in his book Start-Up Century that the 20th-century model of working for a single large firm for most of one’s career is breaking down. Just as automation once shifted workers from farms to factories, AI and digital tools are now automating layers of corporate middle management and administrative work, pushing more people towards independent and entrepreneurial paths.

Policymakers are finally catching up. Just today, Pat McFadden revealed that the Department for Work and Pensions will spend £5 million over the next two years on mentoring benefit claimants in how to set up a business bank account, register for VAT and put together a business plan.

This great transformation is the subject of our new report, Starting Out and Starting Up, supported by Sage and launched in the House of Lords on Wednesday with Kanishka Narayan MP (Minister for AI) and Dr Ben Spencer MP (Shadow Minister for AI).

Drawing on Cebr’s economic analysis of Sage’s 2.2 million payroll records from 111,700 businesses, alongside official statistics, the report shows that the payroll route into work is narrowing. Since 2022/23, the number of employees aged 16 to 24 has fallen by 129,200, a drop of 3.7%, while the number of employees of all ages has risen by 1.7%.

At the same time, more young people are working for themselves. The self-employment rate among 16 to 24-year-olds in work rose from 4.5% to 5.4% over the same period. Around 193,000 are now self-employed, 27,500 more than in 2022/23, helped by AI tools that cut the cost and complexity of starting.

Support has not followed them. The Youth Guarantee is built around employee jobs, and there has been no dedicated self-employment route since the New Enterprise Allowance closed in 2022.

Cebr models what would happen if 5% of young people not in education, employment or training (NEET) — around 50,000 — moved into self-employment between 2027 and 2029. It would add £4 billion to output by 2029, with every nation and region gaining.

We make three recommendations: a Startup Allowance pilot for under-25s built around mentoring, a £3,000 Youth Enterprise Grant inside the Youth Guarantee matching what an employer already receives, and a youth strand of Help to Grow focused on using AI to start and run a business.

Leading Questions

Following World of Work 2026 in September, we’re pleased to be supporting MHR and Telegraph Media Group again with their next Future of Work breakfast. The theme of the free event is “Transforming from the top: cultivating culture, resilience and growth in a rapidly changing business environment.”

Applied futurist Tom Cheesewright, who has worked with Google, Meta and Nasa, will chair a panel with three guests. Fiona Hnatow, Chief People Officer at the University of Portsmouth, led the university’s strategic reset. Harriet Molyneaux, founder of Intero, advises senior leaders at FTSE 100 companies. Yvonne Maher, Chief Growth Officer at Cognito, chairs the Women’s Irish Network. They will look at how leaders can move from reactive management to building clarity, trust and resilience in their teams. The panel is followed by a Q&A, and there’s a networking breakfast beforehand.

It runs on Tuesday 10 November at Telegraph Media Group’s offices in Victoria. It’s open to business owners, C-suite, directors and senior leaders. There are only 60 places, and Telegraph Media Group will pick attendees to give a balanced mix of industries. Register your interest before Friday 30 October. Register here.

Three Big Ideas #72

🍄 Philip Salter, Founder

Universities used to be judged on teaching and research. Over the past four decades, a third goal has joined them: creating economic value through spinouts, licensing, contract research and partnerships with industry. Academics call this the “entrepreneurial university”. But how well do we understand it?

Writing in The Journal of Technology Transfer, Martin Bliemel analyses which keywords appear together across 5,857 articles from 1969 to 2024, finding 240 topics in seven themes. Research on the entrepreneurial university, he finds, has gone through five overlapping eras: technology transfer, clusters, innovation systems, social systems and human-centred systems.

Entrepreneurship education is now the largest area of focus, making up 12% of the literature, while technology transfer is at 11% and shrinking. The language has shifted from “transfer” towards “exchange” and “collaboration.”

Tellingly, the biggest gap in the literature is university administration, leadership and strategy, with no highly cited papers. As Bliemel puts it, this is “arguably the one area that drives (or constrains) the others.” He suspects much of universities’ entrepreneurial activity has emerged organically, or even “by accident,” and has “simply mushroomed in niches within the university on their own.”

From hundreds of conversations with entrepreneurs, universities and ecosystem builders, I’m convinced he is right. Despite some heroic exceptions, entrepreneurship is under-resourced and undervalued in most universities.

The Office for Students’ May 2026 report found 36% of English higher education providers were in deficit in 2024/25, forecast to rise to more than four in ten in 2025/26. Universities need to earn more beyond tuition fees and government grants, yet it is hard to be strategic when money is tight.

But focus, they must. Some researchers want to widen the concept, arguing that the entrepreneurial university needs to be replaced by a so-called “sustainable entrepreneurial university,” putting societal and environmental impact on a par with economic impact. Bliemel argues, convincingly, that the existing concept “remains perfectly adequate.” Its definitions have consistently centred on creating economic value and reducing reliance on government funding. Stretch it to cover sustainability and wellbeing, and the entrepreneurial university loses its distinctiveness.

Universities no longer have the luxury of leaving entrepreneurship to mushroom. They need hard strategic thinking — built on evidence of what works in university administration, leadership and strategy.

🛩️ Mann Virdee, Head of Science and Technology

I spent yesterday at Rolls-Royce in Derby learning how jet engines work and how they’re made.

I was there with this year’s cohort from the Foundation for Science and Technology, and saw the evolution from early piston aero-engines named after birds of prey (Eagle, Hawk, Kestrel, Merlin) to the more familiar gas turbines and jet engines named after rivers (Avon, Trent, Derwent, Nene).

Rolls-Royce began over lunch at Manchester’s Midland Hotel on 4 May 1904, when the electrical engineer Henry Edmunds introduced Charles Rolls to Henry Royce. Rolls soon agreed to sell every car Royce could make.

The two men could hardly have been more different. We were told how Royce sold newspapers at ten, and an aunt paid for his apprenticeship at the Great Northern Railway until her money ran out. By his own account, it gave him some skill as a mechanic but left him lacking commercial experience. By contrast, Rolls was an Eton- and Cambridge-educated aristocrat who ran a London showroom selling imported cars. A third man, the commercial managing director Claude Johnson, became known as ‘the hyphen in Rolls-Royce’.

We were told that developing a new engine used to take about 10,000 engineers three years. Today it takes 1,000, but still about three years. The future of innovation may involve a million ‘virtual engineers’ and just one day. With more founders using AI to go it alone, one might wonder whether a modern Royce would still need a Rolls.

A working paper from Seoul National University suggests it depends how far you want to go. Its authors studied more than 160,000 launches on Product Hunt, a website where founders unveil new apps and users vote for their favourites. After ChatGPT arrived in November 2022, average monthly launches by solo founders more than doubled, from about 1,300 to 2,800, while those by teams rose from about 350 to 540. Almost all solo launches were one-offs, never updated within a year.

But teams strengthened their hold at the top. They made up 53% of each day’s ten most popular launches, up from 50%. Product Hunt is software, not jet engines, and the authors caution against generalising to industries that need heavy investment. Still, they conclude that AI makes it easier to start a venture but not to build one, which depends on several people’s combined knowledge and experience. AI can stand in for a Rolls at the launch stage but it’s far less clear that it can replace the customers, connections and commitment he brought.

That matters most for young people, whose routes into employment have narrowed since 2022. Our new report with Sage, Starting Out and Starting Up (see Ian’s Big Idea below), finds that the share of working 16–24-year-olds who are self-employed has risen from 4.5% to 5.4%. But the Youth Futures Foundation has found that companies set up by young people with an older relative as a co-director survive longer than those they set up alone.

If AI inflates the number of one-off launches, counting how many young people start businesses might tell policymakers less than counting how many go on to build teams. AI may make it easier to be Royce without a Rolls, but that’s no guarantee of the kind of longevity that has made Rolls-Royce an engineering powerhouse.

🌱Ian Ng, Researcher

It has been a perfect storm for young people. Many will have been hoping for a bounce post-Covid, but so far the experience has been a supply-chain shock, a cost-of-living crisis and a weak job market coupled with uncertainties brought by AI. The number of young people not in education, employment or training (NEET) and economically inactive reached its highest level in the 21st century in Britain, and the Government is attempting to fix this, partly in a drive to bring down the welfare bill.

Much has been written about the double whammy of the real-terms increase in the National Living Wage and the rise in employer National Insurance contributions, both increasing the cost of hiring. While we are all for reducing the cost of hiring, we also believe that payroll employment is not the only viable route for young people, which brings us to Starting Out and Starting Up, our latest report on making self-employment a route into work for young people.

One of our policy recommendations is the creation of a £3,000 Youth Enterprise Grant, mirroring previous government schemes that supported self-employment in response to a weak labour market. The Enterprise Allowance Scheme in the 1980s paid unemployed people £40 a week for up to a year to start a business, supporting more than 325,000 people, including Creation Records founder Alan McGee and artist Tracey Emin. The Coalition Government revived the idea in the form of the New Enterprise Allowance (NEA), giving eligible benefit claimants a weekly allowance and business mentoring while they set up. Around 161,000 businesses were supported by the NEA over the decade, until the end of the scheme in 2022.

Annual costs of the NEA varied with uptake of the scheme, from £22.1 million in 2017/18 to £58.8 million in 2013/14. However, the Treasury could make long-term savings — our proposed grant would cost less than the amount paid annually to a Universal Credit claimant. As the Milburn Review found, the longer a young person is out of work, the harder it becomes to help them back. If the £3,000 Youth Jobs Grant paid to employers is worthwhile for getting young people into work, then the same should apply to supporting some young people to start a business and potentially go on to create jobs for others.

Labour pressed the then Conservative Government on the cessation of the NEA when in opposition; indeed, this was led by the current Business Secretary Jonathan Reynolds and Seema Malhotra, now a member of the Treasury Select Committee. Stephen Timms, now Minister for Social Security, spearheaded the Work and Pensions Committee’s call for the then Government to “develop a new self-employment support scheme”, saying that “starting a business could return [many people] to the labour market”.

Having made the case for self-employment support in opposition and on select committees, Labour is now in a position to act on it.

Foreign Exchange

Every year we ask a simple question: where were the founders of Britain’s fastest-growing companies born?

This year, Job Creators 2026, in partnership with Penningtons Manches Cooper, found that 54 of the UK’s 100 fastest-growing companies have at least one foreign-born founder or co-founder. The part that those born outside the UK play at the very pinnacle of entrepreneurship is beyond dispute.

And they are weighted towards the biggest hitters. Drawing on Beauhurst data, those 54 companies are worth a combined £15.84 billion, 70% of the total for the top 100.

Of the 225 founders behind the top 100, 98 (44%) were born overseas. That’s up from 42% last year and more than double the foreign-born share of the population. They hail from 35 countries across six continents. The US is the most common birthplace, followed by Italy, then Germany and India. No single country accounts for more than a tenth. Most of the 54 are built alongside British-born founders — 29 were started by British-born and foreign-born co-founders together.

I wrote up the findings for Forbes this week, and the founders we interviewed make the case better than any statistic.

Alexandra Birch-Mayne, the South African-born co-founder of Edinburgh’s Aveni, co-authored a 2016 paper on byte pair encoding, a technique whose variants are now used in most large language models.

“Birch-Mayne credits her background with her drive: ‘I don’t trust that I will be OK. I pursue opportunities vigorously because I do not have extended family or resources to back me up, and culturally in South Africa that kind of behavior is common.’ … Her verdict on the immigration system is blunt. ‘It has been very expensive and unfriendly to people who are high value and can bring a lot of money to the UK.’”

Tamar Gomez came from France for a PhD at Imperial College London and built Ankar AI here rather than in Paris, for the engineers, the investors and the path into the US market. Her co-founder’s visa needed a third-party endorsement and annual progress reviews.

“Gomez points to an oddity in the system: ‘It’s easier for us as a company to sponsor skilled workers than it was for my co-founder to get a visa. Our skilled workers get a visa way quicker than my co-founder did, which is a bit counterintuitive when you think about it.’”

Tim Chong moved from Australia in 2018, picked London over New York and co-founded the rewards credit card company Yonder after finding that, without a UK credit report, he was an undesirable customer despite a good job and a great credit score back home.

“When his application for indefinite leave to remain was held up by processing delays, the government’s Global Talent Taskforce stepped in to resolve it. ‘Without their help, the uncertainty would have significantly impacted the business,’ Chong says.”

The immediate problem is uncertainty. Last November’s consultation on earned settlement proposed doubling the standard wait from five years to ten for most work visas. It closed in February with more than 200,000 responses, but founders are still waiting to hear how it will affect them.

The case for sweeping restrictions has weakened. Net migration has fallen from a peak of 944,000 to 171,000 in 2025, its lowest level since 2012 outside the pandemic. As Pat Saini, head of immigration at Penningtons Manches Cooper, says: “When uncertainty persists, it becomes harder for entrepreneurs to commit fully to building their future in the UK.”

The report’s first recommendation is simple. Publish the consultation response, with a firm start date. Beyond that, we call for Graduate visa holders to get an extra 12 months while an endorsing body assesses their business for the Innovator Founder visa. We also recommend opening the High Potential Individual visa to graduates of INSEAD, HEC Paris, IIT Delhi and Dartmouth. High visa costs are a false economy, putting off those with their pick of countries: a founder moving with a partner and two children pays £18,694. We argue for bringing those costs down for founders and their first hires.

We also recommend replacing the Innovator Founder visa’s “new and innovative” test with one of viability and growth, and making processing times binding. And we propose stress-testing new visa routes before they launch, rather than opening them, watching them get abused and shutting them down.

None of this would increase net migration, and almost all of it could be done without new legislation. As Tamar Gomez said in her case study:

“If you have a good education, a great professional track record, a company with some form of investment already — in the millions of pounds — it should be easier.”

Seven Up

Thank you to everyone who has already filled in our Entrepreneurs Survey. If you haven’t, there are fewer than two weeks until John Healey delivers his first Budget. The survey asks which changes you would most and least like to see, and what you expect the Budget to mean for your business.

Previous waves have already shifted the debate on tax. After the 2024 Budget, seven in ten founders told us they knew another entrepreneur considering leaving the UK. That kind of evidence only exists when founders tell us. It takes under seven minutes and you can answer anonymously. The results go to ministers, officials and journalists. Take the survey here or click below. Extra kudos to those who forward it, or share it on social media or in a founders’ WhatsApp group.

Have your say

Way Founders

We have recently revamped our Support for UK Entrepreneurs page and would be keen to know what’s missing. We send it to every founder who signs up through our website, and share one section here each week with over 13,000 readers — scroll down for this week’s, on funding — so we want it to be as good as it can be. Drop me an email with your ideas.a

Transfer Window

Andy Burnham told the Innovation Nation Summit in Manchester this morning that the Government will legislate so that startups and scale-ups can hire who they want without non-compete clauses standing in the way. He called it “the Bosman ruling for the innovation sector”. More details will come in the Budget on 28 October. Thank you to all of you who backed the Free to Start and Scale letter, which we signed and which I wrote about last week.

Burnham also said Britain cannot afford for its startups to sell up rather than scale, and that more is needed on tax to keep founders here. As if by magic, today we open our new Entrepreneurs Survey with Public First, asking founders which tax changes they would most like to see at the Budget.

It takes under seven minutes, and the results go to the ministers, officials and journalists shaping policy for founders.

Have your say

Built Regardless

On Wednesday we published the Female Founder Ambition Series Report, kindly supported by the Jessica Vollman Foundation and drawing on roundtables and a run of interviews.

As Sarah Vollman, Primary Advisor at the Jessica Vollman Foundation, said:

“The founders described a system that wasn’t designed with them in mind, and the ingenuity it took to build successful businesses regardless.

“Many of these barriers affect all small firms, but for female founders they compound. A founder who bootstraps can age out of SEIS [the Seed Enterprise Investment Scheme] before she ever pitches an investor. One who pays herself a £5,000 salary to avoid employer National Insurance can get less than half the maternity pay of a founder on £12,570, and miss out on 30 hours of funded childcare.

“Modest, workable changes within the current framework would close many of these gaps. Progress should be measured by whether female founders find the system easier to navigate, not by the number of initiatives announced.”

The Jessica Vollman Foundation was introduced to us by our Adviser Kajal Sanghrajka. Kajal was Jessica’s friend and business partner. Mike Vollman, Jessica’s father and an Adviser, describes the series as honouring his daughter’s legacy, which you can read about here. Thank you to all the founders who took part in the series, many of whom are Members of the Female Founders Forum. As Kajal said at the launch on Wednesday, “we’re only just getting started.”

Speakers’ Corner

We are pleased to reveal who’s opening our next two report launches. Job Creators 2026, with Penningtons Manches Cooper on what international talent contributes to Britain’s entrepreneurial ecosystem, will be opened on Wednesday 14 October by Max Wilkinson MP, Liberal Democrat Home Affairs Spokesperson, and Joshua Reynolds MP, Liberal Democrat Investment and Trade Spokesperson.

A week later, Starting Out and Starting Up, with Sage on the rise of self-employment, will be opened in the House of Lords by the Rt Hon Kanishka Narayan MP, Minister for AI.

I hope to see some of you there.

Three Big Ideas #71

⚗️ Mann Virdee, Head of Science and Technology

In 1662, the newly chartered Royal Society of London appointed the natural philosopher Robert Hooke its first Curator of Experiments. Its Fellows had no shortage of questions about the natural world. What the Society lacked was someone whose job it was to test them.

Hooke was expected to bring three or four experiments to every meeting and to try out those the Fellows proposed. He was extraordinarily productive. He built the air pump for Robert Boyle’s experiments on the ‘spring of the air’, the work that led to Boyle’s law. He coined the word ‘cell’ after seeing them through a microscope of his own design. But even Hooke could not keep up with the Fellows’ ideas.

More than 350 years later, AI may be recreating Hooke’s problem.

That’s the implication of AI in Science: Early Insights, a new study by researchers at Google, Google DeepMind and MIT FutureTech. It draws on around 15 million Gemini interactions, more than 2,600 specialised scientific models and a survey of 637 researchers in the US and UK.

Scientists are big users of AI. In the US, science occupations turn up in Gemini conversations about 2.7 times as often as their share of employment would suggest. Nearly half of those surveyed use AI daily, and the average respondent saves almost seven hours a week.

But the bottleneck in scientists’ workflow hasn’t so much disappeared as shifted: 44% say their main constraint has shifted downstream over the past two years, into lab work, clinical validation and field data collection. This research finds that physical experimentation and data collection is now the most commonly cited constraint, named by 24%. And 41% report a growing backlog of untested hypotheses, against a quarter whose backlog has shrunk.

The survey isn’t necessarily representative, and the authors rightly point out that AI enthusiasts may be more likely to respond. But both the downstream shift and the growing backlog are strongly correlated with how intensively respondents use AI. As the authors put it, AI may have increased the number of viable hypotheses, but not necessarily the means to test them.

Perhaps a more interesting finding is about the direction rather than speed of scientific research. Almost half (49%) say AI is steering them towards safer, more incremental projects, against 28% who say it lets them take on riskier questions. The authors suggest a possible ‘streetlight effect’. AI lowers the cost of tractable, data-rich problems the most, so riskier questions, where data is scarce and validation is physical and expensive, get crowded out.

We might assume the scarce ingredient in science is ideas. This paper suggests this is becoming less true. What’s scarce now is the modern Curator of Experiments. That is, the labs, instruments, technicians and automated facilities that test hypotheses. As AI makes the easy-to-test questions cheaper first, it also shapes which questions get asked.

🔍 Philip Salter, Founder

In March, Innovate UK published a new prospectus that reorients it towards deep tech in priority sectors, as those who came to our Audience with Tom Adeyoola, Executive Chair of Innovate UK, will know (better than most). Central to the pitch is for Innovate UK to become a “trusted due diligence engine” for the UK’s deep tech ecosystem.

Last month, the Innovation and Research Caucus published Science as Substrate. Written by Nesta’s Innovation Growth Lab, it links 29,262 Innovate UK projects to a global corpus of over 40 million papers and classifies each research topic as niche, emerging, active or mature. Since 2020, 90% of the AI funding it could classify has gone to projects built on slow-growing niche or mature topics, while the fastest-growing parts of the AI literature attract almost no funding.

Several of the “AI” topics are broad catch-alls, and the authors note that Innovate UK has rarely said what research maturity it is aiming for. Even so, the finding shows why a sharper deep tech strategy matters.

Science as Substrate also points to a deeper problem. Innovate UK doesn’t publish what happens to the companies it funds, so outcomes have to be reconstructed after the fact by outside researchers from company filings and commercial databases.

When an earlier Caucus study tried this, 13,500 of its 59,048 grants couldn’t be traced to a company at all, because the registration numbers were missing or wrong. The same report found a mixed picture on impact: Innovate UK-funded firms grew faster in employment and turnover and patented more, but there was no clear effect on productivity, and funded firms were more likely to go insolvent, which the authors suggest may reflect riskier ventures.

Innovate UK knows how to fix this. In 2018 it committed to tracking outputs and expected outcomes for every project it funds. Its own evaluation framework calls randomised trials the most robust method, and it has allocated innovation vouchers by lottery, with an evaluation designed alongside the Innovation Growth Lab, the team behind Science as Substrate.

We made a similar case last year in Full Speed Ahead, our report on Britain’s 500-plus accelerators and incubators. We called for a dual-track assessment that follows both how companies perform and how founders develop. The same applies to Innovate UK: it should track outcomes for every company it backs under the new strategy. It should also avoid turning any single number, such as follow-on investment, into a target.

The prospectus has the logic right. Deep tech is hard to invest in because the risk is technical, and Innovate UK can call on technical assessors most investors can’t. Its endorsement could end up worth more to a company than the grant itself. For that to happen, Innovate UK needs the data to show how its picks have done, and Science as Substrate shows how far it has to go.

🗺️ Ian Ng, Researcher

Successive governments have banged the drum about regional inequality, from Boris Johnson’s levelling up to Andy Burnham’s “good growth in every postcode”. That ambition now runs through every corner of government, including public procurement and innovation policy.

The 2025 Industrial Strategy called itself “unashamedly place-based”. In the same year’s Spending Review, Keir Starmer’s Government committed £86 billion to R&D over four years, rising from £20.4 billion in 2025-26 to £22.6 billion by 2029-30. So it is tempting for the Government to kill two birds with one stone: why not focus innovation funding on left-behind places?

New research by Johan P Larsson and Johan Grip suggests the two goals pull against each other: mission-oriented innovation policy may inherently exacerbate regional imbalances. Missions concentrate resources where a breakthrough is most likely, which tends to mean cities and established hubs. Cities benefit from the agglomeration of talent, capital and institutions such as universities, hospitals and major firms.

The cycle is self-reinforcing: early concentrations attract further investment, talent and institutions. And because missions are, at their core, about accelerating progress, money flows most easily to places that can absorb it quickly and show visible results within short timeframes; most lagging regions lack that absorptive capacity. The researchers conclude that if missions succeed, their benefits concentrate in hubs and cities; if they fail, the money will still have acted as an expensive stimulus for those same places.

UK funding already follows this pattern. UKRI, the UK’s largest public research funder, spent only half of its money outside the Greater South East in 2023-24, while ARIA concentrated two-thirds of its funding in London, the South East and the East of England.

I have written about the dangers of ‘everythingism’ in the previous edition and the edition before last, so I won’t repeat it here. As former Science Minister Lord Vallance put it, curiosity-driven research must be funded purely on excellence, excellence will always cluster, and funding should “absolutely not” be spread evenly.

To argue otherwise is cakeism: it abandons funding on excellence and undermines the value-for-money case for spending public money on research. I fully accept that the Treasury could spend money to support left-behind places, but the Government should be honest that innovation funding is the wrong tool for it.

There is one caveat. When Britain’s cities were built through decades of agglomeration of talent, institutions and capital, demand for clean energy on the scale AI requires had not yet appeared on the horizon. This is the logic behind AI Growth Zones, which use faster planning and grid access, rather than research grants, to steer data centres towards places with abundant clean energy.

The North Wales AI Growth Zone is the prime example. Anglesey is not known for attracting talent or capital, but its geography could give it new life. Wylfa will host Britain’s first three Rolls-Royce small modular reactors, due to supply the grid from the mid-2030s. Off Holy Island to the west, the Morlais tidal scheme is preparing to put its first devices in the water. Offshore wind farms in the Irish Sea off the North Wales coast add further capacity, and the Growth Zone’s Prosperity Parc site on Anglesey is earmarked for data centres. This is the reindustrialisation of the 21st century.

But geography alone won’t do the job. In July 2025, the Government rejected zonal pricing and kept a single national wholesale electricity price, so a data centre next to Wylfa pays the same wholesale price as one on the outskirts of London. The Government addressed the problem with electricity discounts for data centres in AI Growth Zones. Rather than ministers deciding region by region who gets cheap power, locational pricing would let abundant clean energy pull investment towards it. The Government should be clear-eyed that innovation funding in itself cannot level up left-behind places, but the factors that determine a growth hub may have changed.

APPG for Entrepreneurship APPG for Entrepreneurship Newsletter: October 2026

Neither House of Parliament sits again until next week. But with the Budget looming large on 28 October, we couldn’t resist a newsletter before the end of the conference recess.

There is always a fair amount of speculation ahead of a Budget, which impacts the behaviour of entrepreneurs well before the Chancellor utters a word. In a new report, Tax Policy Associates estimates that around £45 billion of gains were brought forward ahead of the October 2024 Budget, helping push 2024–25 taxable gains to a record £127 billion, 82% above the year before.

That might sound like a windfall for the Treasury. But those gains would otherwise have been realised over the following years and taxed at 24%; instead they were taxed at 20%, at an estimated cost of £1.4 billion to £2.4 billion. Dan Neidle, founder of Tax Policy Associates, expects the same happened before the 2025 Budget, and that it is happening again now. Nor is the instability new. Over successive governments, the headline capital gains tax rate has been raised, cut, raised again, and split into multiple sub-rates.

Research has found that Brexit uncertainty reduced business investment. More broadly, the academic literature shows that periods of high policy uncertainty coincide with lower business formation, investment and innovation.

After the 2025 Budget, the then Chancellor told the Treasury Committee there had been too much speculation and too many leaks, much of it inaccurate and very damaging. A leak inquiry followed.

Leaks aren’t the only problem, though. Newspapers, think tanks, business and lobby groups can fall into the habit of driving speculation. Sometimes it’s to head off changes they oppose. But sometimes it’s because taking credit for stopping a measure is a way to demonstrate influence, even when the measure was never really on the table.

This is familiar ground for the APPG. Back in 2018, our report on Tax Reform included cross-party forewords from Liam Byrne MP (Labour), then Chair of the APPG for Entrepreneurship, and Colin Clark MP (Conservative), who wrote that the Treasury and HMRC must ensure policy “has longevity”. The report found uncertainty over the Annual Investment Allowance (AIA) made it hard for firms to plan investments spanning three to four years. Since then, the 2022 Autumn Statement set the AIA at £1 million permanently, full expensing was made permanent in 2023, and both were confirmed in the 2024 Corporate Tax Roadmap.

In 2023, our APPG report Funding to Flourish argued that uncertainty about the future of the Enterprise Investment Scheme (EIS) and Venture Capital Trusts (VCTs) was already having a negative impact, because founders couldn’t plan fundraising rounds without knowing whether the schemes would survive their 2025 sunset clause. The report was launched in the Lords with Lord Leigh and the then Shadow Business Minister, Bill Esterson. The 2023 Autumn Statement extended both schemes to 6 April 2035, with support from both sides of the House, giving entrepreneurs and investors certainty about their future.

More recently, founders at our evidence session on R&D tax relief described years of near-constant change creating a chilling effect on legitimate claims. Unlike the AIA and EIS/VCTs, R&D relief has had no lasting commitment to stability in its rules. As the cases above show, stability commitments can be delivered and kept across governments.

Governments of all hues have used roadmaps to reduce speculation. Examples include the Coalition’s 2010 Corporate Tax Road Map, the 2016 Business Tax Road Map and the Corporate Tax Roadmap 2024. Their record is mixed, but each was an attempt to give business a clearer view of the years ahead.

In 2017, Better Budgets, a report by the Chartered Institute of Taxation, the Institute for Government and the Institute for Fiscal Studies, argued for one main fiscal event a year and a more open process. Some of its authors have since said tax policy making has gone backwards.

No government will tie its hands on every tax, but there is no reason Chancellors can’t commit to stability on most business taxes for the length of a Parliament, and rule out ideas they have no intention of adopting.

Whichever Chancellor manages to quell business uncertainty, now or in future, will find entrepreneurs ready to invest, hire and build the growth every party says it wants.

Advisory Board Update

Latest news, research and events from our Advisory Board

The Entrepreneurs Network is hosting three report launches in October. On 7 October, it launches the JVF Female Founder Ambition Series report, which examines the barriers female founders face across the full lifecycle of building a business. Job Creators 2026, produced with Penningtons Manches Cooper and launching on 14 October, looks at foreign-born founders building Britain’s fastest-growing businesses.

On 21 October, it launches Starting Out and Starting Up: Making self-employment a route into work for young people. The Entrepreneurs Network is also heading to Oxford on 15 October for an informal morning meetup for Ecosystem Builders.

London Life Sciences Week 2026 will be held from 15 to 20 November, bringing together the global life sciences community for a week of events, showcases, breakthrough innovations, investment opportunities and networking.

Beauhurst Insights has published two new reports. Unlocking Value from AI, produced with BGF, looks inside growth businesses, while Financing the Future, produced with Barclays Eagle Labs and Barclays’ Group Policy Development team, examines the role international capital plays in helping UK companies grow.

Universities UK is conducting a survey to understand the key decisions made by innovators, entrepreneurs and investors, and the policies they need.

The Enterprise Research Centre (ERC) will present the results from its Longitudinal Small Business Survey on 18 November at The Shard, reflecting on trends over 11 years of data. It is also holding its annual conference on the State of Small Business in Britain on 1 December, focusing this year on small businesses and local economic resilience. Separately, the ERC has just published What determines the mobility of university spinouts? An interview-based study of spinouts in the Midlands.

Flo State

For a stretch in her twenties, Tara Chandra paid £450 a month for a room in Hackney, working shifts as a barista to cover her bills while building an organic period-care brand out of her flat.

She had originally come to London from the US to study at the London School of Economics, and it was there, mid-degree, that she found herself talking to her now co-founder Susan Allen — one of just six women on their course — about the difference in supermarket shelves back home.

Why was organic period care easy to find on any shelf in LA, but nearly impossible to track down in the UK? The two women decided to unpick that question themselves, and it wasn’t long before Chandra’s idea for her master’s dissertation became a real-life business case for Here We Flo.

Today, Here We Flo turns over £15 million a year, split roughly 70/30 between the UK and US, selling plant-based period care alongside newer lines in bladder health and sexual wellness. It sits on shelves at Boots, Whole Foods USA, Tesco, Asda and Sainsbury’s, backed by founders and executives from brands such as Unilever, Method and Charlotte Tilbury.

Below, Tara talks us through the funding hurdles that have shaped Here We Flo’s growth, as well as what it takes to build a transatlantic business as someone who’s chosen to call Britain her home.

What we discussed

  • Tara’s path from musician to founder, and the ‘toilets at LSE’ moment that led to the founding story of Here We Flo.

  • The gap she and her co-founder spotted for organic, plant-based period care in the UK.

  • How Here We Flo went from a £14,000 Kickstarter to a nationally stocked, £15-million-revenue B Corp.

  • Why the UK’s independent retail scene served as an early growth advantage.

  • How EIS and SEIS enabled early fundraising, and where UK scale-up capital falls short for consumer businesses.

  • The real cost and complexity of the US retail system, and why Here We Flo initially stayed deliberately focused and remote with its expansion.

Lessons for founders

  • Build proof of concept before you need capital. Tara didn’t wait for funding to prove Here We Flo worked. Instead, she got into independent Hackney retailers by walking in and cold-emailing buyers directly. That early traction, built on relationships, is what helped make later fundraising possible.

  • Lean on other founders who have experience. Tara points to informal WhatsApp and Slack groups among UK brands operating in the US, where founders share brokers, trade-show tickets, and compliance contacts. She sees this peer network as one of the more practical resources available to founders expanding transatlantically.

  • Be honest with yourself about what US expansion actually costs. Tara warns that trying to launch with major US retailers on British funding budgets doesn’t work, because the capital a US business spends on one launch can match what a British business raises to fund its whole three-year plan. Her advice is to go in with a clear-eyed view of the capital and operational commitment required, rather than assuming the UK playbook will translate.

Lessons for policymakers

  • Back specialist scale-up funds for the consumer sector. Tara points to only a handful of UK consumer-focused funds that are generalist and later-stage, leaving a lot of potentially successful investments unfunded or with suppressed demand. She contrasts this with the US, where there is significantly more capital in sector-specific funds, meaning founders aren’t competing against hospitality chains and pet food companies for the same cheque.

  • Extend lending support to early-stage consumer businesses. Tara points to a basic funding gap: UK lenders have little appetite for extending credit to early stage, often unprofitable, businesses, forcing her to raise expensive equity just to fund inventory. In the US, Tara can access lines of credit for exactly that — support she called a huge unlock when Here We Flo finally got it this year. R&D tax credits are the nearest UK equivalent, she notes, but don’t apply to most consumer businesses.

The founding story

You went from a musician to LSE to founder — how did that journey lead you to starting a business in the UK?

My undergrad was at Columbia in economics. I really loved economics because it seemed to be a way that you could solve social problems with data and have a higher likelihood of being taken seriously if you can show a positive economic impact, which in a capitalist society is very important.

I had also trained as a musician from the age of four, most seriously in opera and then jazz. I was in a music performance programme at Columbia. I was also taking quite a lot of classes because I was interested in different things, including my major in economics, but also international policy.

The side effect of that was that I was eligible to graduate in about two years, which gave me an amazing opportunity to think about what I wanted to do next when I was 20, which was two years earlier than I thought I’d have to confront that question. And like most 20-year-olds, I don’t think I made a very good decision. I had been looking at a sustainable development PhD programme at Columbia, but instead turned that down — which I think would have been very interesting, actually — and decided to become a professional musician.

If you think being an entrepreneur is hard, try being a music artist.

I had representation from big companies, but, like most young music artists, I was mostly ignored after signing unfavourable contracts and left to build my career without the support I naively dreamed a big entertainment company would bring. Most musicians, even those with representation, also have to “bootstrap” — fund their own albums and tours upfront and, hopefully, make the money back later. As an indie musician, you spend most of your time working for those incredible moments of being in the studio or being on stage. It’s fantastic for building work ethic and resilience, I’ll give you that! On the whole, I found the music industry a very frustrating experience, albeit peppered with moments of great creative fulfilment and passion. That also got me thinking more about business and how messed up the music industry was, quite frankly, and how much injustice there is in that system.

After a few years of that, I had the real luck and honour of getting to work with a music producer in London I really admired, Steve Booker — he did Duffy’s first record, John Newman’s first record. I loved London and realised it was where I wanted to be, and at the same time, my experiences in the music industry made me realise I wanted to feel empowered around business and management. So I decided to do my master’s at the LSE, and on the first day, I met my co-founder and best friend, Susan. We were alphabetically assigned next to each other. There were only six women in that programme at the time, and only a few of us in our 20s, so we were naturally pushed together.

Within a few weeks, we were in the toilets between classes at the LSE, and Susan was expressing frustration that every single business case we studied — Toyota, Disney, Lego, United Airlines, John Deere — was a similar story: Michael Eisner staring out the window wondering what he was going to do about Disney’s share price. There were never any women mentioned because they were all owned and operated by men. Susan said: “Hey, forget the PayPal mafia; we should start a business — we should start the feminist mafia.”

We were in our mid-20s, so it was a really silly thing to say, but it kicked off everything.

Where did the specific idea for organic period care come from?

I was still that sort of California hippie, real music artist vibes — vegan, talking to people about organic and regenerative farming, drinking almond milk and kombucha. Susan likes to make fun of me and say I did it before it was cool. And I remember saying, what about organic period care? I used to buy that in LA, because you could get it anywhere, but when I came here, it was really hard to find.

It shouldn’t be hard to find. You should be able to get it on the mass market the same way you can get natural baby wipes, organic hummus, organic apples, gluten-free bread, plant-based milk, even in a Tesco Express or Sainsbury’s Local. But clean and green was really missing from women’s intimate healthcare.

Susan was really interested in this idea, and that was where it all started.

Here We Flo’s early days

What did those first two years of actually building Here We Flo look like, from your dissertation to your first production run?

I used the business case for Here We Flo as my master’s dissertation. In that process, we did focus groups, business research, but also environmental and health research. I was living in Hackney, and there were just so many cool people around at the time — one of my friends was also a musician who had just become co-founder of a business called Minor Figures, which at that time was doing cold brew coffee, and now it’s a huge plant-based milk company. So it was a really interesting time to be in Hackney, seeing all the great stuff happening in food and drink.

I kept working in music, as a songwriter for other people, and really enjoyed that. But I couldn’t put down the idea of Flo, and it was super creatively fulfilling. We did all the branding, packaging, and design without having any background in any of it — we taught ourselves. I had been selected by LSE as a graduate entrepreneur, which gave me the visa and the time to keep exploring and developing the idea, and it started to slowly get traction.

We did a Kickstarter, back when that was a thing, but only raised £14,000 because it was really just pushed to our network and friends. We did our first production round of 6,000 pots of tampons and started selling shop to shop in Hackney and Islington, to lots of the independent places, and learned ground up how to run a consumer business. The first two years, 2018 to 2020, were just Susan and me doing it out of our flatshares, hand-delivering to shops, slowly onboarding a warehouse, getting into Planet Organic, WHSmith Travel — the smaller steps.

How has the vision and team behind Here We Flo’s products evolved as the business has scaled?

Things really started to accelerate in 2019. We got listings in 2020 for Boots, Holland & Barrett, and Ocado, so everything started to come together. We raised around a million and a half of seed capital in February 2020, and then spent the last six years scaling up through every kind of global and macroeconomic event and struggle — supply chain crisis, the sluggish broader economy — and managed to fundraise and grow throughout all of that, while refining our vision.

We have always had the people and planet focus. Within people, we are most passionate about supporting girls and women, not only in our bodily cycles but also in our culture, through encouragement, confidence and empowerment. We weren’t interested in solving just a product problem; we wanted to stand for something as a brand and say something - in a unique voice - to the users. That just didn’t exist in the sector at the time.

Then on the product and planet side, we started off thinkingabout the materials that our bodies deserved, both from a plant-based side but also from an efficacy side. If you go too far one way or the other, it’s distorted.

So we really wanted to think about creating products that were both reliable and responsible, that were efficacious,but that also solved a brand, materials and communications problem.

Now we’re a team of 32 women, and it has been such an honour learning from all these amazing people. The smartest thing we did was just hire people who are way cleverer and more experienced than we were, and put ourselves in a position of learning from them while also sharing our vision and keeping everybody aligned with our mission, vision and values.

The empowerment piece has been a huge part too. We’ve been lucky to hire women who are interested in working for Flo because it’s not just about the materials we use — it’s also this idea of a period care company that talks about things, shows up in the world and interacts with culture the same way an embedded brand like Nike or Coca-Cola would.

Women’s health deserves that share of voice, so we think a lot about how we can be funny, feminist and fierce, as well as how we can approach everything with positivity, humour and transparency.

Why the UK

You grew up in Silicon Valley and studied in New York. Why did you end up building Here We Flo in the UK rather than going back to the US?

There are a few reasons. One, I have always loved London, because of the creativity and the diversity around me. It has always felt like there is so much creative, fresh air to breathe. And for a big urban global city at the time I moved, it was affordable.

I was living in a closet in Hackney, paying £450 a month for my room, including bills, so I could work as a barista whilst getting the business off the ground and cover my bills. To put that in perspective, when I was living in LA and New York before, forget it.

My friends who moved back, even earning crazy high six-figure salaries with great stock options, can’t actually live in any of the places where we grew up. They live two or three hours outside. So, compared to the Bay Area, to New York and LA, London felt not only more inclusive and open, more diverse and creative, but it also felt more liveable. I have since moved to Cambridgeshire, to a tiny village, because the cost of living in London has gotten nuts. But at that time, that was definitely not the case. So I really appreciated that.

The second thing is, I was at that age — 24, 25 — when you’re looking for new experiences, thinking about where you want to settle, and it’s so much about people and community. I never quite found my people in New York or LA. I moved to London and very quickly felt like I had found a great community of people I’m still friends with today, whether from the LSE or from my music community, which made it much more appealing and interesting to stay.

Beyond lifestyle, what was the business case for building in the UK?

Because I was studying at the LSE, I was looking at the business case for Here We Flo for the UK and Europe, specifically the UK.

With hindsight, I can say the UK is an amazing place to start a business due to regulatory ease of starting a business, strong network effects, London having easy links to continental Europe (more relevant before Brexit!), SEIS/EIS funding schemes and good movement of labour (at least compared to the US, where immigration is complex and contentious). But honestly, when we were starting Here We Flo, we had such a strong bias to action that we were focused on the quick wins of getting into market - that’s where the UK really stood out.

The UK has a real advantage as it has a lot more independent retailers per capita. I was able to go into independent grocery stores or off-licences that also sold period care for last-minute needs - you know, the corner shop. They’d be owned by local families in Hackney — Turkish, Kurdish, Polish immigrants, or people born and raised there who wanted to support a local business, even if it was from a young woman with an American accent, because I lived in the neighbourhood. So I could walk in and get traction and then product-market fit.

I never would have been able to do that in the States, because there’s no such thing as local for me when I had to drive 20 minutes to get to a big, very corporate Albertsons, Safeway, or Kroger. Now I know how to get into local and independent retailers in the US, but I also have a field sales team, a distributor that specialises in that. Without capital, I don’t think I would have been able to do that.

It was also easier to get proof of concept in the UK for consumers specifically, due to population density. Similarly, the retailers are much easier to get in touch with in the UK — this isn’t the case anymore, but I used to just ring up Superdrug, having no idea what I was doing — I’d say I have a product I’d love to talk to you about, and she’d say, can you send me an email? But I could do that — I could just email the buyer at Boots. In the US, the retailer system is usually done through brokers, and when there are so many brands, it’s very difficult. They get a thousand emails a week from new brands alone, so they can’t look at them all.

What’s been the hardest part of funding Here We Flo’s growth in the UK?

What helped our growth early on was EIS and SEIS, which is an incredible UK-based programme. The real issue we’ve had is the scale of capital, especially within consumer.

There is a tiny ecosystem for funding consumer businesses in the UK at the scale-up stage, and it has gotten much smaller over the last few years that we’ve been scaling. What is there is quite frankly very generalised, whereas in the US it would be, “here’s a $100M consumer fund that just does health and wellness.”

It was a very real problem that when we’d go to market to talk to the few consumer specialist funds that exist in the UK, they were all later stage focused. They’d say they start around £5 million in revenue and write £5M cheques, but then when you’d meet with them at that stage, they’d say we’re writing minimum £10M cheques for businesses doing a minimum of £15M in revenue. Then it became £20M at £20M+. So the goalposts kept moving, but in part because the pool of relevant funds was small and static. And you’d be competing with a pitch from a fashion brand, a makeup line, a candle line, a hospitality business, a pet food company, a soup company, an app — and now AI companies that orient themselves around the consumer - no specialisation.

Ultimately, the scale-up capital, specifically in the consumer sector, because it’s underdeveloped, is really lacking, and that’s what I find interesting — I’m part of Buy Women Built, and there are so many incredible brands you probably shop and didn’t know were female-founded.

But they’re still spending so much time, most of their year, trying to raise scale-up capital via £10,000 to £25,000 cheques from EIS-focused angel investors. And they need to raise millions of pounds as they grow to make it to a meaningful scale; doing that £10k cheque at a time…That is insane, especially given the amount of time that it takes away from actually growing your business. If we’d had growth capital to accelerate faster, we could have been paying the UK a lot more tax, too.

We of course have sector-specific investment vehicles in the UK, as well as generalist funds with dedicated sub-segments, informed by sector experienced people that build Britain’s expertise in these areas. Consumer could benefit from these structures and segmentation: food and drink, wellness, beauty, fashion, consumer tech, hospitality, etc.

Beyond raising equity, what other funding gaps do you think UK policy is missing for consumer businesses like yours?

Well, it’s really just an extension of the same problem, capital shortage: working capital provision for consumer businesses specifically.

We’ve had to raise millions of pounds of equity over the years to spend on inventory, because the UK does not have a high risk appetite for lending to early-stage or growth-stage — meaning unprofitable — businesses for things like that.

The only one was SVB, now HSBC Innovation Bank, but even then, they want to see profitability, which is not always the focus when you’re in your high growth stage. Whereas in the States, we’re eligible for so much working capital finance, whether that be solutions like lines of credit or debt to fund it.

When we finally accessed working capital finance earlier this year, it was a huge unlock for us. You can focus the angel money you raise — even £10,000 at a time! — through EIS on your actual marketing and growth team. R&D tax credits are probably the equivalent from an impact perspective, but they don’t apply to most consumer businesses.

I’d also want to see if the data shows that most consumer businesses are founded or co-founded by women, because you often become a founder for something you use but think you can improve— and around 80% of global consumption is controlled by women, according to Nielsen.

It goes without saying that I want to see more female founders in every sphere. But I’m curious whether you’d redress some of the gender funding gaps if there were structural financial supports for consumer businesses in the same way there are for other sectors. And as TEN has written about, successful founders, FMCG or otherwise, tend to invest in other entrepreneurs, so other kinds of tangible financial support in our sector would be part of a virtuous business cycle.

Crossing the pond (again)

At what point did you realise you needed to go into the US, and how did that expansion actually begin?

We were pulled over to the States by retailer demand during the Pandemic. The UK and Europe shut down with lockdowns, whereas the US was much more open. They didn’t have lockdowns the same way we did. We started engaging in 2020, and around 2021, began slowly putting things in place and built up.

We started with a geographic focus, and for us it was the Pacific Northwest, because there were lots of natural and organic retail chains. We got a warehouse set up — had to do that without meeting anyone, because of Covid, which was insane — and then used our investor network to find a sales agent who helped us for our first 700 doors or so.

Then we mainly did proof of concept for the first year or two, and about four years ago we launched with Whole Foods USA, who reached out to us — but we were already in the USA in a very small way, already set up with their distributor, because we’d already done some early-stage legwork, some early market traction, in a similar way we had in the UK. That is the approach I really believe in.

What’s your advice to British brands about the operational and financial reality of scaling in the US?

Doing a big mass-market retailer launch on British funding budgets doesn’t work, because you can’t afford to invest the same way as your American competition will.

A US consumer business will go out and raise a $5 million round just for launching in Target. British consumer businesses can raise £5 million for their whole three-year plan.

So my advice would be: if you’re a British business thinking about going overseas, it is a completely different retail market, and you need to be prepared for that. You need to figure out whether you’re willing to invest in hiring on the ground in a market with a 2-week notice period and higher salaries - plus the cost of healthcare.

Why have you chosen to stay remote and focused rather than following other UK brands who’ve moved founders to the US?

I’ve seen a lot more UK consumer brands moving founders out to the US in the past year — Misfits, Trip, Lovecorn, Wild — opening up, hiring here, moving people over there. It’s really exciting to see these great British brands entering the US market.

Our focused strategy of starting with US natural and independent retailers — Whole Foods, Sprouts, and a long tail of independents — has allowed us to do almost everything from here so far, with remote working and some agency support in the States. Consumer expansion in the US from over here is admittedly hard to resource in the UK, because it’s a totally different system. You’ve got your broker, your field sales team, then your distributor, who needs managing in their own right — and the retailers pull from them, and there’ll be hundreds of them. It’s complex. We’ve built the knowledge internally through experience and our US network.

It’s easier to do a launch with Walmart or Target because it’s one account, but that one account will have a fines-and-fees culture — plus no retailer has perfect execution in the market, so you’ll need to pay someone to check that the stores you’re in actually have your products on the shelf. That can cost $25,000. You need to know the right agency that does those compliance checks, and they’re not easy to Google.

So there are layers and layers and layers about how the US retail and consumer products market works. I’d say to anyone truly serious about it — get a US funding partner if you can, talk to other brands from here or Europe that have gone successfully into the States, because we do all share resources — we have WhatsApp groups and Slack channels where we go, “Hey, we’re going to Expo West this year, does anyone have an extra ticket?” or “Hey, who do you use for your Costco broker or your deductions management service?”

It’s a whole different universe, and that’s why we stayed laser focused in the States, building up a successful business in the sales channel that’s our best fit before branching out.

This series is run in partnership with the Jessica Vollman Foundation, a non-profit founded to honour the legacy of the late CEO, founder and advocate for women in entrepreneurship: Jessica Vollman.
Free Rein

As members of our growing WhatsApp community will already know, we backed and pointed entrepreneurs in our network in the direction of two letters from different corners of our ecosystem this week. Both have something in common that should pique the interest of the Chancellor — they’re about removing friction rather than spending money.

The Free to Start and Scale letter argues outdated employment practices are holding back Britain’s start-ups and scale-ups. In March 2025 I wrote about Nando de Freitas posting on X arguing Europe should copy California in banning non-competes. This week, he was a founding signatory of a letter calling for exactly that. As the letter argues:

“Labour mobility is a classic collective action problem. Competition for technology talent is fierce, and no company wants to lose out. Not all start-ups and scale-ups can unilaterally disarm, when the dominant technology companies use contractual restrictions to make competing harder. But the current status quo is bad for workers, businesses, and the British economy.”

To be clear, non-competes aren’t a priori bad. It’s really an empirical question. But one where the evidence points towards a ban. Enforceability does give firms a reason to invest in people and ideas, raising intangible investment by around 8%. But innovation has more inputs than company investment, and non-competes suppress mobility and new firm formation, which the evidence suggests matters more. After all, as Mann Virdee argued, Silicon Valley hasn’t done too badly from California’s 1872 law against enforcing non-compete clauses.

In 2023, the Government rejected a ban and settled on a three-month statutory cap. The cap was never legislated. Instead, in November last year the Department for Business and Trade went back to the beginning, publishing a working paper on four options including an outright ban. The Competition and Markets Authority responded in February by backing reform.

Read the letter and add your name here.

The second letter, organised by Odin, calls for a UK Exempt Reporting Advisor regime. It’s prohibitively expensive to start a VC fund in the UK. A $10 million US fund loses roughly 4.5% of commitments to admin and compliance over its life; the UK equivalent can reach 14%. This goes some way to explaining why the median US venture fund was $21 million in 2024 against £70 million in the UK.

Today a new fund manager needs the Financial Conduct Authority’s permission before raising a penny, or has to rent it from a firm that already has it. Odin’s proposal is that a narrow category — funds that don’t borrow, that lock investors in for a fixed term, and that raise only from institutions and sophisticated investors — should simply have to notify the regulator instead.

Read, sign and respond to the consultation here.

Share

Daisy Chain

Daisy Cooper MP, Deputy Leader and Treasury Spokesperson for the Liberal Democrats, has written inviting you to respond to the party’s Plan to Get Britain Growing Again. It covers investment, enterprise, innovation and trade, and proposes a new Department for Growth bringing together economic, tax, business and trade policy. Feedback goes through a short form.

To be clear, we would circulate this sort of opportunity for any party, and have done so. Our job is to get founders in front of whoever is drafting the policy. If you have a particular allegiance, say so when you join us — we sometimes pass things on directly to a party, and it helps to know who wants what.

Message from our Partner

At Fora, we create flexible workspaces that empower ambitious businesses to thrive. With over 70 locations across London, the UK and Germany, our spaces are designed to fuel productivity, creativity and growth.

Now, we’re bringing that vision to The Jellicoe at King’s Cross — a dedicated hub for founders and fast-growing companies. Here, flexibility meets opportunity: scale at speed with agile workspace solutions, connect with a curated community of entrepreneurs and investors, and enjoy all the perks of a Fora membership, from wellness spaces and hospitality-grade service to events that open doors.

Surround yourself with innovators and global tech giants in one of London’s most exciting neighbourhoods.

If you’re building the next big thing, this is where you want to be.

Discover Fora with a free Day Pass

Rates of Passage

The Budget is on 28 October, the earliest since 2021. Alongside it comes the fiscal devolution roadmap, and the share of business rates that mayors will keep from April 2027.

We all know by now that this Government is committed to moving money and power out of Westminster, something we’re in favour of (as long as places keep the proceeds of growth). But there isn’t much cash sloshing about. Quite the opposite. The Government’s fiscal headroom has collapsed (again): KPMG puts it at £11.6 billion, while Deutsche Bank puts it at £8.5 billion — down from £23.6 billion.

It is being reported that Treasury officials spent a fortnight in workshops with business groups on high street tax measures, and that raising the small business rates relief threshold is a central option.

Two changes are under consideration. The first concerns who pays nothing at all. A property with a rateable value of £12,000 or less is currently exempt from business rates, with partial relief tapering away to nothing by £15,000. The proposal would lift the exemption to around £17,000 — the figure the threshold would have reached had it been uprated with inflation over the decade it has been frozen — and the taper to £20,000, taking thousands of small firms out of the tax and reducing the bills of thousands more.

The second concerns how fast bills rise for everyone else. April’s revaluation pushed some rateable values up sharply, in places by as much as 80%, and transitional relief phases those increases in. For smaller properties, this is capped at 5% this year, 10% in 2027/28 and 25% in 2028/29, plus inflation. Healey is said to be weighing a longer phase-in.

Strong arguments can be made for both changes. But business rates retention begins in April 2027, and each of these narrows the base for mayors.

The roadmap has a second question to answer. Jim O’Neill, who advised Burnham informally in recent months, has raised a caution of his own. As reported in the Financial Times (paywall), he said devolving to places that are not ready could be a recipe for disaster — noting that of 37 devolution submissions from local areas during his time as a minister, four were credible. “This is probably the single most immediate challenge they’ve got,” he added of Burnham’s team. “With a lot of local areas putting their hands up saying ‘what about me, me, me’, they’ve got to be tough about it.”

Property developer Mike Ingall, whose firm Allied London built Manchester’s Spinningfields in close partnership with the city council in the 2000s, says: “My fear is if we devolve to all the mayoral departments, towns, cities, are they good enough?” … “That’s not a criticism of everyone, it’s just a question. Will we have to go through a process of educating these other local government officials? Because my experience elsewhere is not good.”

Mike Emmerich’s review of growth-capable devolution, which reports in October, published a first paper in August detailing the problem. Where Whitehall doubts an authority’s capability, departments retain detailed controls; those controls consume local capacity; the capacity never develops; the doubts are confirmed. Across 242 urban areas in 14 European countries, the OECD found productivity higher where the quality of government is higher, with the effect strengthening as local autonomy rises — but with weak institutions, greater autonomy makes outcomes worse.

Emmerich is no sceptic. He calls the assignment of income tax particularly welcome, and argues that strategic authorities need a tax base commensurate with the role now envisaged for them. The Budget will be a test of whether the Chancellor can get the balance right.

Share

Data Points

Our friends at techUK have published a report bringing together chapters from different organisations on the role of technology in UK growth, covering everything from adoption and skills to regulation, data, investment and trade.

I recommend reading it in full, but I will point you specifically to the chapter from the Royal Academy of Engineering (RAEng), which was led by our Adviser (and former colleague) Anastasia Bektimirova.

The OECD’s Open, Useful and Re-usable Data Index scores the UK below the OECD average, with a particular weakness in turning available data into usable data. The UK’s three flagship data programmes — the National Data Library, Smart Data schemes and infrastructure data — are run separately by different bodies. The chapter recommends a joint delivery framework, tested on problems that need data from more than one of them.

Join us

Trinity Test

Blick Rothenberg, one of our Strategic Partners, is holding an event on Thursday, 1 October, as part of the Lloyds British Business Excellence Awards, and has asked us to share it with you.

It is a chance to hear from entrepreneurs, share experiences and make connections. It runs from 2.30pm at Ten Trinity Square Private Club in London. Register your interest here or contact Abi with any questions.

Three Big Ideas #70

📈 Philip Salter, Founder

We all know that slow growth means lower material living standards than would otherwise be the case, but what are the other consequences? Matt Clancy digs into the evidence on non-material consequences over at What’s New Under the Sun.

The work of Besley, Dann and Dray shows that faster growth goes with more trust in government and less perceived corruption, with larger effects in democracies. Slower growth explains somewhere between a quarter and two-thirds of the trust gap between American millennials and boomers. And as Acemoglu et al. show, living in a democracy only builds support for democracy when that democracy delivers.

The bigger risk for entrepreneurs is zero-sum thinking. Chinoy, Nunn, Sequeira and Stantcheva find that those who grew up in slow-growth years lean towards the view that people can only get rich at the expense of others. This isn’t confined to the left or the right: zero-sum thinkers back both more redistribution and tighter immigration, which might help explain the politics of the past decade.

Worse, this mindset sticks. Trust in government rises and falls with recent growth, but zero-sum thinking sets in early: it’s the growth you experience in your first 20 years that counts. By surveying 20,400 Americans about four generations of family history, the authors trace zero-sum thinking back through ancestors’ experiences too, including how much upward mobility they had and whether they were immigrants. A slump today can shape the outlook of voters not yet born.

That should worry Britain, where GDP per person is 29% below where it would have been had the 1955–2008 trend continued. The British 18-year-olds reading this have lived their whole lives in this economic quagmire.

For those of us who have lived a bit longer, it isn’t just rose-tinted nostalgia. Up until the financial crisis, it was reasonable to conclude that things could only get better.

Not everything shows up in the numbers, but as Eamonn Ives has argued here previously, GDP correlates with longer life expectancy, lower infant mortality, higher educational attainment, reduced extreme poverty, and many other things that matter.

Growth also keeps alive the belief that one person’s success need not be another’s loss, and without that belief, it’s hard to win the argument for rewarding the people who take risks.

🌾 Mann Virdee, Head of Science and Technology

Maris Piper, for decades Britain’s most widely grown potato, was bred by the state at the Plant Breeding Institute in Cambridge to resist potato cyst nematode. That’s also the case for much of Britain’s wheat. In fact, the institute’s wheat varieties accounted for 90% of the UK market when the government sold the Plant Breeding Institute to Unilever in 1987. The sale reflected a belief that industry, not the state, should pay for this type of near-market research.

However, private breeders find it hard to make money from wheat. As the wheat flower has both male and female parts, it pollinates itself. And because wheat seed grows into the same crop year after year, farmers can sow seeds saved from last year’s harvest. By contrast, maize has separate male and female flowers and is easy to hybridise, but seed saved from a hybrid won't grow into the same crop, so farmers have to buy fresh seeds every season. You could say hybrid maize seed is like a subscription, whereas wheat seed is a one-off sale and customers can grow their own. Without some other way to get paid, breeders have less reason to invest and innovate in non-hybrid crops such as wheat.

In 1985, the US Patent and Trademark Office ruled in Ex parte Hibberd that seeds and plants could be patented. This is the context for a new NBER working paper, Flowers of Invention, by MIT’s Jacob Moscona, who treats the ruling as a natural experiment. He compares crops such as wheat and barley (where patents in effect turned the seeds into a subscription) with crops such as maize (where hybrids had long done that naturally).

The paper finds that in the decade that followed this ruling, new variety releases for the newly protected crops more than doubled (up 119%) compared with hybrid crops, and yields rose 11%. The increase was driven by private R&D rather than public spending. Tellingly, it came from crops replanted every year or two, where a patent turns farmers into repeat customers. Farmers in counties suited to those crops spent more on seed but their land values and profits rose, meaning the better seed more than paid for itself. On the most conservative estimate, patent rights added 7.5% (roughly $80 billion) to the value of US farmland by 2002, though larger farms benefited disproportionately.

The paper’s findings now have a British test case. In July, Defra confirmed that PiperPlus, a new disease-resistant Maris Piper developed at the Sainsbury Laboratory in Norwich, qualifies as precision bred. BioPotatoes, a startup part-owned by the lab, plans to take it to market. But potatoes, like wheat, have little natural moat. Farmers can keep back tubers from one harvest to plant the next.

In the UK, new varieties are protected by plant breeders’ rights rather than patents, and these are deliberately weaker. Farmers who replant their own tubers pay only a reduced royalty and rival breeders can use protected varieties to develop new ones. That keeps seed cheaper and lets breeders build on each other’s work, but Moscona’s findings suggest the price may be less invention.

⤴️ Ian Ng, Researcher

OpenAI reportedly expects to burn through $280 billion by 2030. It is an extreme case of a familiar pattern in the startup world, where high-growth companies endure periods of losses before breaking even. Investment in equipment and talent drags cash flow down before revenue catches up, forming a J-curve if the company manages to scale.

New research by Hellmann, Montag and Tåg examines whether differences in financing capacity affect the cash flow and growth trajectories of startups. Studying the Swedish startup scene, they find that those backed by American VCs experience substantially deeper operating losses after investment, followed by higher sales from around the third year. These startups also receive more capital than their non-US VC-backed counterparts. The authors link this to US VCs having deeper pockets, as they manage on average SEK 37.3 billion more than non-US syndicates. Nationality of the VCs alone does not explain the difference in the performance of startups. The authors find that startups receiving investment from a large non-US VC show a similar combination of deeper losses, higher sales and more funding.

The authors then turn to the EU’s Scaleup Europe Fund, from which Britain is reportedly being blocked. However, we don’t start from a bad position among European countries. According to an EIB study cited in the paper, the US had 137 VC funds larger than $1 billion between 2013 and 2023, compared with 11 across the European Union and 10 in the UK alone. And some of the largest UK pension funds are considering to commit capital to a new £1 billion UK Scale-up Fund with the British Business Bank. As the research suggests, funds with sufficiently deep pockets are needed to sustain losses in the early stages.

There are pitfalls to avoid. The fund should be run on commercial terms, with the single objective of returns from scaling the best companies, rather than being loaded with the objectives that littered the government’s announcement: good growth in every postcode, reindustrialisation and so on. As with public procurement, ‘Everythingism’ tends to achieve little. There should also be no pressure to deploy the £1 billion quickly. The Centre for British Progress cites evidence that the best UK VC funds are already oversubscribed, so rushing to spend would push money down the quality ladder.

Hellmann, Montag and Tåg warn against confusing continuity of financing through years of losses with unconditional continuation. Continued financing must remain conditional on credible growth milestones, and political objectives risk muddying the waters.

The Bostrom Line

While existential risk from AI has hit the news a number of times over recent years, this is the week it finally went properly mainstream, with even the King raising concerns. It’s been a long time coming.

All the way back in 2018, when the House of Lords Select Committee on Artificial Intelligence flippantly dismissed the warnings of thinkers like Nick Bostrom, I wrote that this should be a serious concern for policymakers. At the very least, we should keep an open mind about this.

To be clear, thinking this risk is legitimate doesn’t come with a ready-made set of policies, nor does it mean that AI companies need to pause or even slow down. Some argue the opposite — that democratic countries should do everything to win this race in order to mitigate the risk of despotic countries winning.

To that end, our friends at the Centre for British Progress have just released a report looking at how the UK can lead on AI. Among other things, it recommends pricing grid capacity and opening transmission connections to competition, and letting data centres run on their own gas while they wait for the grid. It also calls for a Building Britain Act to fast-track planning in AI Growth Zones, with one environmental assessment per zone rather than per project.

Diary Notices

Some dates for your diaries:

Do you want to be proactively invited to our events? If so, fill in this form so we know what you’re interested in. We have a lot coming up — and there is something for everyone.

Pillar Talk

The Invest in Women Taskforce has published its 2026 manifesto, Driving Lasting Change, built on five pillars: gender balance in investment policy, better representation among decision-makers, transparency, tax incentives and education. The fifth draws on Ideas to Impact, specifically our finding with Barclays through the Female Founders Forum: fewer than 8% of UK spinouts had all-women founding teams, against more than 75% all-male.

Among other things, the Taskforce calls for the seven-year Enterprise Investment Scheme (EIS) eligibility limit to be removed and a carry-forward mechanism introduced for unused EIS and Seed Enterprise Investment Scheme (SEIS) allowances. Read it here.

Leave to Trade

The Cedar Review, an independent review into refugee entrepreneurship led by Small Business Britain, has now reported. I sat on its Steering Board. People seeking asylum can’t work at all for 12 months, and after that only as employees in a narrow set of listed roles — self-employment is excluded outright at every stage, whatever the person did before they arrived. Read it here.

Sukhpal Singh Ahluwalia, who supported our first Job Creators report in 2019, is a reminder of what that contribution can look like. He arrived from Uganda in 1972 at 13, fleeing Idi Amin, and spent more than a year in temporary accommodation. He was working the markets at Petticoat Lane and Liverpool Street by 15, and in 1978 opened a single car parts shop in Willesden. Euro Car Parts eventually ran to more than 300 sites and 12,000 employees before selling in a deal reported at up to £280 million.

Board Room

When Parliament returns after the party conference season, the Advisory Board of the All-Party Parliamentary Group will resume its monthly meetings. For this group, we’re looking for those in trade and membership bodies, associations, research centres and universities, as well as think tanks and quasi-public bodies. If you’re keen to be considered, drop Mann Virdee an email.

Home Grown

Jade Bentwood spent a decade advising high-net-worth women through divorces, exits and other upheavals. Then she went on maternity leave and found there wasn't the support in place for working women navigating life transitions.

So she started hosting other women at her house.

Together, they’d sit on the kitchen floor, holding their newborn babies on their laps, and talk more openly than they ever had in the office. The same thing came up every time. Nobody knew what came next, or who was going to help them work it out.

There was no blueprint, so she made the nearest thing to one: she matched the women in front of her with others from the same industry who had already been through it. That became TALO, a mentoring platform for women going through life and career transitions. We spoke about what it took to build it.

What we discussed

  • Why mentoring works where traditional coaching often doesn’t, and what women need when navigating career transitions.

  • What a useful support ecosystem for female founders looks like in the UK.

  • How going to market before the product was perfect led to some of her best clients, and why the best cash comes from your customer.

  • What the romanticised version of founder life leaves out when you’re a mother of two young children.

Lessons for policymakers

  • Make paternity leave long enough and paid well enough to be worth taking. Fathers get two weeks, paid at the statutory rate, and the framing is that they are helping out at home. Jade argues men who take real time out come back as better leaders, with a clearer sense of what their female colleagues are dealing with — and that until the entitlement is substantial and properly paid in its own right, few will take it.

  • Direct dedicated equity funding to female-led businesses. Women building credible, scalable companies aren’t reaching capital at the same rate as men. Jade wants funding structured specifically to reach them, and more women in the roles that decide where it goes.

  • Shift more public sector procurement to SMEs. Jade acknowledges this isn’t gender-specific. But a public sector contract can transform an early-stage business, giving it stable revenue that takes the pressure off raising before you’re ready.

Lessons for founders

  • Start before you’re ready. Talk to your customers before anything is polished, even before you have all the answers. The gap between what you think you’re solving and what people actually need only closes through real conversations, and from Jade’s experience, the earliest ones are often the most valuable.

  • Build an informal board before you build a team. Identify people who are invested in the mission and tap into their knowledge in a structured way. People are generous with their time when they believe in what you’re building, and that can carry you further than any formal structure.

  • Find your tribe, carefully. Not every network delivers, but for Jade, the right community is one that leaves you feeling energised and with something tangible. Look for founders a little further ahead, willing to share the real vulnerabilities alongside the practical advice.

The founding story

You spent a decade in professional services before founding TALO — a mentoring platform supporting women through transitions such as fertility, maternity, leadership and menopause. What was the journey from there to here, and where is TALO now?

I worked in investment management for 10 years, running a women’s division that looked after high-net-worth women going through life transitions such as divorces, successful exits and professionals looking to be more strategic with their wealth. I really loved it. I loved the helping people part, the opportunity to engage with such a diverse mix of incredible women, and how we could empower them through knowledge. It felt like a business within the business.

I then went on maternity leave with my first child and found that transition quite hard from a professional standpoint. A lot of my identity was wrapped up in work, and being off and detached from that, I found it very difficult. I felt quite isolated, from the business I'd grown and built, and I thought to myself, I cannot be the only woman feeling like this.

So I started having events at my house with big groups of women, mostly from professional services, sitting on the kitchen floor with babies on laps, talking really vulnerably and openly about what they were feeling and what their companies were doing to support them.

I looked around at these amazing, highly capable women who were all saying the same thing: they weren’t sure how they were going to make it work, they were thinking about not going back, they couldn’t see the blueprint. There weren’t enough women they could talk to about it.

I thought, this is such a waste of talent. These women had worked in their industries for 10+ years and were all future leaders. So I started matching them to mentors, including other women from the same industry who had lived that experience and could give real, practical guidance. The feedback was amazing, and not just for the mentees, but for the mentors too.

Why do women going through these transitions need peer support specifically — what is it that a mentor who’s been there can offer that conventional support can’t?

I did a huge amount of research while we were building the business, and what I realised was that a lot of the coaching platforms out there weren’t working.

What women need in those very vulnerable moments when they are navigating something quite raw is lived experience from someone that they genuinely relate to because they have walked in their shoes. They want to be told what worked for that individual, so they can then take the bits that feel relevant and authentic to them and use them for their own journey.

We get feedback over and over again, and it’s always consistent. A mentor has to be someone who isn’t in your business, because there is a psychological barrier to how open and vulnerable you’re going to be because of the optics of how that might look internally.

So giving women the space to share, while hearing from someone they really admire and respect, gives them the validation and the permission to say, actually, I need your help, I need your guidance.

That practical side allows them to have tangible things to do tomorrow. In these pivotal transition moments, the practical side and the relatability are the bits that people take so much value from.

Building TALO

What’s one decision that you can now see was disproportionately important, but wouldn’t make most people’s list of obvious founder advice?

I was a solo founder, and I came from an environment where I got a lot of my energy from other people. I enjoy

that back and forth and being able to bounce ideas off someone. But when you’re a founder in the early days, you really don’t have that. It is very much you in your mind, trying to make sense and prioritise what you think is the most urgent thing that day, which can be quite a lonely place.

People talk about founder loneliness all the time, but for me, the answer wasn’t just putting myself in a co-working space around other founders. What I needed was people who were hugely invested in my success — who wanted to see this grow because they cared about the mission — and who I could talk to when I needed to.

So rather than overcomplicating it with a formal board of advisers, I assembled an informal one — people who cared about what we were doing, whose knowledge I could tap into when I needed it.

I found that to be really transformational because it allowed me to feel like I had a team, and a really experienced team at that. I was blown away by how generous people are with their time when they’re invested in you and the problem you’re trying to solve.

You went out and started building client relationships before the platform was fully ready, and some of those became your best clients. What gave you the confidence to do that, and what did you learn from those early conversations?

My confidence came from having spent a long time in professional services. I understood the challenges our clients were facing and had established relationships with businesses that trusted me and knew how I worked.

That meant I could have honest conversations early on — testing the idea, listening to what clients actually needed and shaping the solution around that feedback. You need those early clients who understand the problem and are willing to take a chance on you before everything is perfect.

I’d also lived the problem first-hand, so I had real conviction in the impact of what we were building. Those early conversations confirmed that this wasn’t just my experience — businesses were seeing the same challenges across their organisations, which showed me we were solving a genuine need.

You’ve built without external funding and are now scaling with employer clients. How did that shape the way you’ve built?

The best cash is the cash from your customer. That phrase has really stayed with me. In the early days, I was able to build TALO, generate revenue and prove there was demand without significant overheads or the need to raise external capital. So for me, it made sense to stay focused on customers and build from there.

The mission has always been about unlocking female potential. The quality of the match and the impact we can have on a mentee’s experience of work is what helps women stay, progress and thrive.

Initially, not raising was a deliberate choice. Then it became a question of: how far can we take this by listening to our clients, generating our own revenue and growing sustainably? So far, that approach has shaped the business we’ve built.

The ecosystem

We hear the “only about 2% of VC funding goes to women” statistic a lot. What have you seen work, for yourself and others, when it comes to finding the right support as a female founder?

I can’t speak from my own fundraising experience because I haven’t taken that route, but I’ve seen female founders around me take very different paths — from angel investment and SEIS/EIS to bootstrapping and VC. The funding statistics for women are still awful and absolutely need to change, but there are opportunities; the challenge is understanding which route is right for you and how to access it.

More broadly, I think you have to find your tribe. The right networks and communities are the ones you leave with something tangible — an introduction, a piece of advice, a different perspective — and feeling energised rather than overwhelmed.

For me, the most valuable support has come from a small, informal board of people I trust, particularly founders who are just a few steps ahead. They’re close enough to the journey to remember the reality of it, share the vulnerabilities as well as the successes, and give practical advice I can actually use.

What does a genuinely useful support ecosystem look like to you?

For me, a genuinely useful support ecosystem has a mix of experience, seniority, backgrounds and perspectives. Different people bring different things — advice, experience, introductions, funding or simply a perspective you haven’t considered — and you need that diversity around you.

It also can’t just be women supporting women. Men need to be part of the conversation too. The same applies to investment panels: having a mix of perspectives around the table leads to better conversations and better decisions.

Ultimately, it’s about creating an ecosystem where people are genuinely open to learning from each other, sharing what they know and, importantly, opening doors for others.

Founder life gets romanticised a lot. What’s the part nobody talks about?

There are a few things. I completely underestimated how much losing a consistent salary would affect me. I came from a stable corporate career, and while that financial pressure creates fire, losing the independence and security of your own income is a real adjustment.

Then there’s the reality of not having a team around you, particularly in the early days. You’re making the big strategic decisions, but you’re also doing the tiny operational things that nobody sees. And there’s no real ‘off’. The business is always there in your head — what you need to do, what isn’t working, where the next client is coming from.

I also don’t think we talk enough about comparison. You’re constantly exposed to other founders announcing funding rounds, new hires, huge growth or big client wins, and it’s very easy to feel like you should be further ahead.

For me, building a business alongside being a mum to two young children has also meant I’ve had to accept that growth isn’t linear.

It’s been important for me to not measure my journey against somebody else’s and focus on building the business in a way that actually works for my life.

Policy

If you could change one thing about the environment for high-potential female founders in the UK, what would it be and why?

I’d change the way we think about paternity leave and, more broadly, the role of fathers in those early years.

At the moment, paternity leave is often framed as a man taking time away from work to ‘support’ his partner. I think we need to completely reframe that.

There’s a wider impact too. When men take meaningful parental leave, they return to work with a much deeper understanding of the pressures their female colleagues and partners are navigating. It can shift priorities, build empathy and ultimately make them better leaders.

Most importantly, it starts to remove the assumption that having children is primarily a woman’s career event. If we want more high-potential women to build businesses, progress into leadership and fulfil their potential, we have to create an environment where parenting — and the career impact that comes with it — is genuinely shared.

On funding specifically, where would you want policymakers to actually start?

In general, move more public sector procurement to SMEs. It isn’t gender-specific, but it would help every smaller business.

If we’re talking about something more targeted, I’d say dedicated equity funding for female-led businesses: actual capital, structured to reach women who are building credible, scalable businesses but aren’t accessing the funding their male counterparts are.

The data on the funding gap is stark. We need policy change, and more women in the roles that decide where funding goes.

Closing and Advice

What’s one piece of advice you’d give to a founder just starting — the kind you wish someone had given you?

Go all in. The moment I fully committed to TALO properly, everything changed. But alongside that, I’d say talk to your customers as early as possible, before you’ve built anything polished, and before you have all the answers.

The temptation is to perfect the proposition first and then validate it. I realised early on there’s often a gap between what you think you’re solving and what people actually need. You can only get that clarity and feedback by talking to your customers.

I do this regularly, and it always gives me new ways to improve and shape what we’re building.

What’s one thing you’ve read, listened to or come across recently that you’d recommend to readers?

The Subtle Art of Not Giving a F*ck by Mark Manson. It sounds flippant, but it’s genuinely one of the most useful things I’ve read as a founder. The central argument is that you have a finite amount of energy and attention, and the skill is choosing ruthlessly what deserves it.

As a mother and founder with multiple plates spinning, you cannot care about everything. This book helps look at what actually matters. For me, it’s been a practical tool as much as a philosophical one. It’s shaped how I make decisions, how I protect my time and stay focused on my goals.

This series is run in partnership with the Jessica Vollman Foundation, a non-profit founded to honour the legacy of the late CEO, founder and advocate for women in entrepreneurship: Jessica Vollman.
Chasing Unicorns

John Healey gave his first big speech as Chancellor on Monday. It set out a broad vision rather than focus on detail. Nevertheless, there was much to welcome — the Fingleton Review on nuclear regulation to be delivered in full and its approach extended into other sectors; a commitment to cut the administrative burden of business regulation by 25% by the end of the Parliament; and judicial review reforms extended from energy to all major infrastructure to prevent the kinds of “vexatious legislation and vexatious litigation” that currently block economic growth.

Healey also set out a commitment to cross-economy sandboxing powers, covering pavement robots to drones to medical treatments — which is in line with what founders told us they needed when we brought together robotics founders with the Regulatory Innovation Office. There is also to be an end to what the Chancellor called the “consultation culture” at the Treasury. These are good signs, but we’ll be watching the Autumn Budget closely on 28 October for more detail. In particular, we’ll be keeping an eye out for the recommendations we submitted via the Treasury’s stakeholder portal earlier this week.

One of the lines that struck me from the speech was that the Chancellor set out “an ambition now to double the number of unicorn firms.” The Hurun UK Unicorn Index 2026 finds 80 unicorns in the UK, worth £242.4 billion, third in the world behind the United States and China, and more than Germany, France, and the Netherlands combined. Dealroom, meanwhile, says it currently tracks 205 unicorns in the UK. Tracxn finds there are 102, using a definition that keeps counting companies after they list or get bought. On top of this, the Chancellor gave no date by which this target of doubling the number of unicorns should be measured against. If a target doesn’t have a baseline or a deadline, it’s a fairly movable goal. Is the target 160, 204, 410 unicorns, or some other number altogether — and over what timeframe?

As we noted in Perennial Gale in June, revisiting Josh Lerner’s Boulevard of Broken Dreams, there are two ways for a government to help venture capital. One is to raise the demand for it by making the country somewhere worth building in. The other is to raise the supply by providing finance. Too often, we choose the latter. On Monday, we saw £150 million from the British Business Bank for scale-ups in the North, as well as a Northern 500 to convene the region’s most ambitious mid-sized firms. But as Keith Griffiths of The Entrepreneur Festival pointed out, the Government shouldn’t confuse writing cheques with creating growth. The cost of electricity, tax levels and bureaucratic burden still need to be addressed.

Healey’s speech also championed the idea of the state as early first customer. As founders have told us, a first public contract can be worth more to a startup than a grant because it’s also an endorsement. But in May we wrote about a British company knocked off G-Cloud for negative EBITDA and a light balance sheet, which describes nearly every growth-stage technology company. Officials looked at it again and reinstated the listing, and yet the rule that blocked it is still on the books. The Government cannot be a first customer when the process is designed to avoid first-time suppliers. If the Chancellor wants the state buying from the next wave, he should undo the financial-health tests that disqualify loss-making growth companies and stop marking bids on everything except the bid.

Corner Shop

Healey told his audience the economy was turning a corner. This morning’s figures have given him something to point to. Monthly GDP grew 0.4% in July, against an expectation of no growth at all, following 0.3% in June. On the three-month measure the ONS prefers, output also rose 0.4% against the three months to April (the eighth consecutive three-month rise) and was 1.3% up on the same period a year earlier.

This growth was down to services, which are up 0.6% over the three months, with professional, scientific and technical activities up 2.1% and information and communication up 2.5%. By contrast, production and construction each fell 0.5%. That’s not ideal for a speech delivered at an advanced manufacturing centre.

Three Big Ideas #69

💾 Mann Virdee, Head of Science and Technology

The year is 1978. The TV show Dallas has premiered on CBS. Over on BBC1, Grange Hill has started, and Kate Bush has released her debut single, Wuthering Heights. The UK Government under prime minister Jim Callaghan has just put £50 million into INMOS, a new semiconductor company in Bristol.

This is the UK’s industrial strategy. Public money, channelled through the recently established National Enterprise Board, to build a British chip industry from scratch. As with most chipmakers of its time, INMOS made much of its early money manufacturing memory.

But it didn’t last. INMOS opened a fabrication plant in Newport in 1982, was sold to SGS-Thomson in 1989, and by 1994 the brand was gone (although the building is still there). The Newport site passed through several owners before being bought by Nexperia, then made subject to a government divestment order on national security grounds. A US company, Vishay, acquired it in 2024.

I thought about this while reading the Semiconductor Sector Study 2026, published this summer and updated last week. On computer memory, which accounts for almost 30% of the global market and is an area where the report sees an opportunity for Britain, it warns that leading British firms face scale-up barriers that could see them move operations overseas — risking a repeat of the UK’s INMOS experience.

Semiconductor design accounts for roughly 80% of UK sector revenues. Manufacturers report that government support is concentrated on the R&D side rather than the capital-intensive work of scaling production. They also stress that high energy costs are damaging their competitiveness.

Manufacturers responding to the 2026 sector survey also reported 18% of their cleanroom floorspace as under- or unutilised, and said that absent labour constraints their production could more than double. One suggestion in the report is to look at Fraunhofer in Germany and Tyndall in Ireland, where shared facilities get long-term support for running costs, not just capital.

🛒 Ian Ng, Researcher

The Government spends roughly £400 billion a year through public procurement and much has been said about how it should use that spending to support wider policy objectives, most recently on backing home-grown innovation.

The Competition and Markets Authority published two reports on public procurement yesterday. Both are filled with case studies of the procedural burden facing SMEs. A digital startup was rejected from the G-Cloud 15 framework, the Government’s key digital marketplace, because it used a Simple Agreement for Future Equity (SAFE) contract. SAFE is commonly used by early-stage startups but in this case was mistaken by the Government as a form of debt. The Startup Coalition later identified over fifty suppliers that had been rejected for the same reason. Separately, an SME with only five employees decided against bidding for an NHS England medical equipment tender due to the administrative burden of having to publish a current Carbon Reduction Plan, undertake an Evergreen supplier assessment, complete a Modern Slavery Assessment, and undertake Cyber Essentials certification. It reported that exemptions for SMEs from some of these requirements can themselves be burdensome to complete.

Loading every tender with competing secondary objectives produces everythingism: nothing much gets achieved, and the bar rises until only firms with the manpower to tick every box can clear it. The Government should heed the CMA’s advice to narrow its priorities to a meaningful number and to be honest about the trade-offs between them. It has been striking the right tone lately, from exempting smaller tenders from social value requirements to limiting the measurement of social value to job creation, skills and local opportunities.

Every procurement review since the Procurement Act 2023 has arrived at broadly the same conclusion: the system has an incumbency bias and a preference for the safety of a giant consultancy. Since April 2025, central government departments and their arm’s-length bodies have been required to set and publish their own three-year targets for direct spend with SMEs, and to report against them annually — a weaker mechanism than a single mandated figure, and one that has so far done little to change who wins the work. The problem, as the CMA identifies, is that reform has focused on rules and processes without touching the incentives facing procurement teams. Changing the rules alone will not be enough; unless the incentives on decision-makers change too, SME targets will go the same way. British investors are already seen as more risk-averse than their US counterparts — the Government cannot afford to be the same.

📈 Sophya Mashkoor, Research Intern

Two studies published in June push back on the idea that total founder control is good and investor oversight is just friction to be minimised.

Researchers at Imperial College London and Emlyon Business School examined 12 companies across 27 US securities fraud cases brought between 2000 and 2023. A separate study from the University of Toronto looked at 654 fraud cases against US venture-backed startups over the same period. Its headline finding is that fraud remains rare overall — but that startups with founder-controlled boards were twice as likely to face fraud charges as those with investor-controlled or shared-control boards.

The Imperial and Emlyon paper’s contribution is a mechanism it calls “façading”, a slow escalation that often starts innocuously. In the first stage, surface façading, founders overstate how successful the company is or is becoming. In reinforced façading, they manufacture evidence to support those claims — one company in the study fabricated customer contracts and invoices to book revenue that did not exist, then used it to raise at a unicorn valuation. In deep façading, the deception extends to the product itself, complete with staged demos.

Investors aren’t always the victims. The researchers describe some of them setting growth expectations so aggressive that founders feel there is no honest route to hitting them. The investors who push founders towards hockey-stick projections are also the ones best placed to catch the deception that follows — but in hot markets they compete for access by conceding exactly the governance rights that would let them do it, which is how founder-controlled boards become common in the first place. The paper argues that investors can unwittingly “co-create” fraud, and that continuing to back founders previously accused of it normalises the behaviour.

The Toronto study also found that startups launched during overheated markets, with weak oversight and thin due diligence, were 19% more likely to commit fraud later — which suggests board control is less a question of founder autonomy than of what market conditions do to governance. The proposed remedies are stronger; holding directors liable when façading happens on their watch, and formal audits of later-stage private companies. Both carry costs, not least making good people warier of taking early-stage board seats, and neither maps neatly onto the UK, where nothing polices private markets the way the SEC does.

Back Catalogue


On Monday, Chancellor John Healey will give his first big speech. Everything briefed about it says it will focus more on vision than policy. That’s fair enough; we are only seven weeks out from a Budget, with the Treasury’s deadline for submissions looming on Wednesday.

Some credit first. The last Budget took two numbers straight from Backing Breakthrough Businesses. The Enterprise Management Incentive (EMI) asset cap went from £30 million to £120 million and the employee limit from 250 to 500. Enterprise Investment Scheme (EIS) and Venture Capital Trust limits doubled, though relief on the latter fell from 30% to 20%. So I’ve delved into our archives to pull out the policies that haven’t yet been implemented.

First, rule out equalising capital gains tax with income tax. As I wrote in May, Entrepreneurs’ Relief went from £1 million to £2 million to £5 million to £10 million, back to £1 million, was rebranded, then ratcheted from 10% to 14% to 18%, the last step landing in April. A 20% charge on unrealised gains at the border was floated last Budget and dropped rather than ruled out. Founders can’t price a 15-year bet against a system that lurches annually. Is it any surprise that our polling revealed that 62% of founders know another founder who left after the 2024 Budget?

Second, restore the Business Asset Disposal Relief lifetime limit to £10 million, where Entrepreneurs’ Relief sat, and tie it to reinvestment. According to our Entrepreneurs Survey, 72% of founders would put the proceeds of a more generous relief into someone else’s startup and 70% would launch another venture. Sweden deferred tax on gains from unlisted shares reinvested in unlisted companies in 2003, left it alone for two decades, and now produces more unicorns per head than almost anywhere.

Third, index the thresholds. Backing Breakthrough Businesses recommended that we uprate the investment and gross asset limits on tax reliefs annually. The EMI limits were set in 2000 and sat frozen until April. Every few years the ecosystem campaigns to drag them back in line with inflation. This should be automatic.

Fourth, fix the plumbing on the venture schemes — three repairs from the All-Party Parliamentary Group for Entrepreneurship’s Funding to Flourish, outstanding three years on. Make SAFE notes eligible for the Seed Enterprise Investment Scheme (SEIS) and EIS rather than voiding relief when they don’t convert within six months. Scrap the 2014 financial health test, which disqualifies any company whose liabilities exceed its assets, or that has spent more than half the capital it raised. And make HM Revenue and Customs (HMRC) ring an applicant with a clarifying question during advance assurance instead of refusing in silence.

Fifth, abolish Stamp Duty Reserve Tax (SDRT). The UK Listing Relief was the right instinct: three years’ exemption for new listings, about £50 million a year, while the 0.5% charge sits on everything else. SDRT taxes the investment and the return on it, including when the return is negative. It doesn’t come cheap — so if not this year, at least set the direction.

Sixth, treat HMRC as growth infrastructure. Making Tax Simple asked for a callback service, on the evidence of a Chartered Institute of Taxation survey in which 94% were dissatisfied with service levels and one in five would give up rather than keep trying to get through. We also suggested surfacing eligible reliefs inside Making Tax Digital software. A relief nobody knows about doesn’t change behaviour, and 74% of the founders we surveyed knew of none they could claim. Take-up would rise and it would cost something, but it would also incentivise the activity those reliefs were set up for.

Seventh, reset procurement rather than layering on it. Building Blocks found single-bid tenders rose fivefold between 2012 and 2018, against procurement worth around 15% of GDP, a tenth of which reaches SMEs. In May I wrote about a British company blocked from G-Cloud for negative EBITDA and a light balance sheet, which is normal for any growth-stage tech company. To its credit, the Government took note and the listing was reinstated. The rule that blocked it is still there.

Eighth, cut the cost of coming and hiring. A founder arriving alone on an Innovator Founder visa pays £6,862, or £18,694 with a partner and two children, with the health surcharge payable up front for the whole visa. June’s reimbursement scheme for scaleups doesn’t cover founders at all. Last year’s Job Creators argued Britain should stop filtering out the people it says it wants. The fees are doing the filtering. More from us on this shortly — sign up for our next Job Creators launch here.

Ninth, regulate sterling stablecoins for growth. A Sterling Opportunity makes the case for principles-based rules on transparency, reserve backing and custody, rather than redemption obligations and holding caps low enough to rule out corporate treasury use. Sterling stablecoins are backed by gilts, and Healey has the highest cost of servicing government debt in decades.

Tenth, close the online marketplace value added tax (VAT) gap. In February we joined 18 other business organisations in calling for a consultation on extending liability rules, where overseas sellers avoid charging VAT and pocket a 20% price advantage. It closed on 18 August and nothing has followed. Reform could recover an estimated £700 million a year.

Rent Free

“Political entrepreneur” is one of those terms with too many definitions to be useful — the oldest being someone who profits by shaping rules rather than by creating value. A new NBER working paper, Political Entrepreneurs, proposes a more flattering one.

Across 26 US states between 2009 and 2023, the paper reveals that more than 40% of state legislators both owned and actively managed a firm. Britain has no comparable figure. The nearest thing is the LGA’s councillor census, which in 2022 found 15.8% of English councillors describing themselves as self-employed or freelance, against 8% of the adult population. Twice the national rate, but nowhere near 40%.

These US “political entrepreneurs” don’t sponsor more bills overall, but they initiate a greater share as first or sole primary sponsor. Nor are they any more likely than colleagues with other business ties to sponsor pro-business bills, or bills endorsed by state Chambers of Commerce:

“Instead, they selectively advance pro-entry legislation, especially bills related to deregulation and innovation rather than antitrust or access to capital.”

In other words, entrepreneurs with political power in the US are more focused on levelling the playing field than on tilting it.

In our Operation Innovation essay collection, David Stallibrass and John Fingleton CBE quote John Kay:

“You can become wealthy by creating wealth or by appropriating wealth created by other people. When the appropriation of the wealth of others is illegal it is called theft or fraud. When it is legal, economists call it rent-seeking.”

As Kevin Murphy, Andrei Shleifer and Robert Vishny argue in Why Is Rent-Seeking So Costly to Growth?, rent-seeking is self-reinforcing. The more of it there is, the more attractive it becomes relative to producing. It also falls hardest on innovators, because new firms need the permits and licences that incumbents have already bought, and the people best placed to extract rents prefer dealing with insiders they know to outsiders trying to get in.

Not that all lobbying is duplicitous. Much of it helps regulators understand what they are regulating, as Stallibrass and Fingleton are careful to say. The trouble is that the same channel serves both purposes, and incumbents have far more practice using it.

Writing on the paper in Network Effects, Eamonn Ives set out three responses: “Political parties could do more to encourage founders to stand for office; governments could make it easier for them to spend periods inside agencies and departments through appointments, fellowships or advisory roles; and policymakers could be more deliberate about bringing entrepreneurs into the room before rules are written, rather than consulting them as an afterthought.”

The third is the one we spend most of our time on. But if you want to be a political entrepreneur in the model of Baroness Lane-Fox, Alex Depledge, Matt Clifford, Emma Jones or Lord Bilimoria, the evidence suggests you would push for market entry rather than for protection.